
 CA
 NZ
 US
 AU
 IND

 UK

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Summary
British Land (LSE:BLND) reported FY26 underlying profit of £294m, up 5%, with EPRA NTA per share rising 4% to 590p and portfolio value up 2% to £10.1bn as at 31 March 2026. LTV increased to 39.2% while occupancy held at 96.9%. The full-year dividend rose 1% to 23.12p, implying a trailing yield near 5.4% on the roughly 425p share price on 13 July 2026, close to the original 5.46% screening figure. Incoming CEO Joanne McNamara starts in September 2026. This is a factual overview, not investment advice.
Key takeaways
- FY26 underlying profit rose 5% to £294m, with EPRA NTA up 4% to 590p and total accounting return of 8.1%.
- Portfolio value rose 2% to £10.1bn, with campuses delivering 12% like-for-like rental growth versus 2% for retail parks and logistics.
- LTV rose to 39.2% from 38.1% and net debt/EBITDA stood at 7.7x, though British Land has no refinancing need until early 2029.
- The full-year dividend rose 1% to 23.12p; against the roughly 425p share price on 13 July 2026, that implies a trailing yield near 5.4%, in line with the original 5.46% screening figure.
- Incoming CEO Joanne McNamara starts on 4 September 2026, succeeding Simon Carter, adding a leadership-transition factor for investors to track.
Introduction
British Land Company PLC (LSE:BLND) is one of the UK's largest listed real estate investment trusts, with a portfolio spanning London office-led "campuses", retail parks and logistics assets. The stock first came onto our screen with an indicative yield of 5.46%, at a time when UK-listed property companies have been trying to shake off years of persistent discounts to net asset value.
This article revisits that starting point using verified, dated figures gathered as of 13 July 2026, drawing on British Land's FY26 results (year ended 31 March 2026) and current market pricing. Where a figure could not be confirmed, that is stated plainly rather than estimated. Nothing here should be read as a recommendation to buy, sell or hold the shares.
Key facts 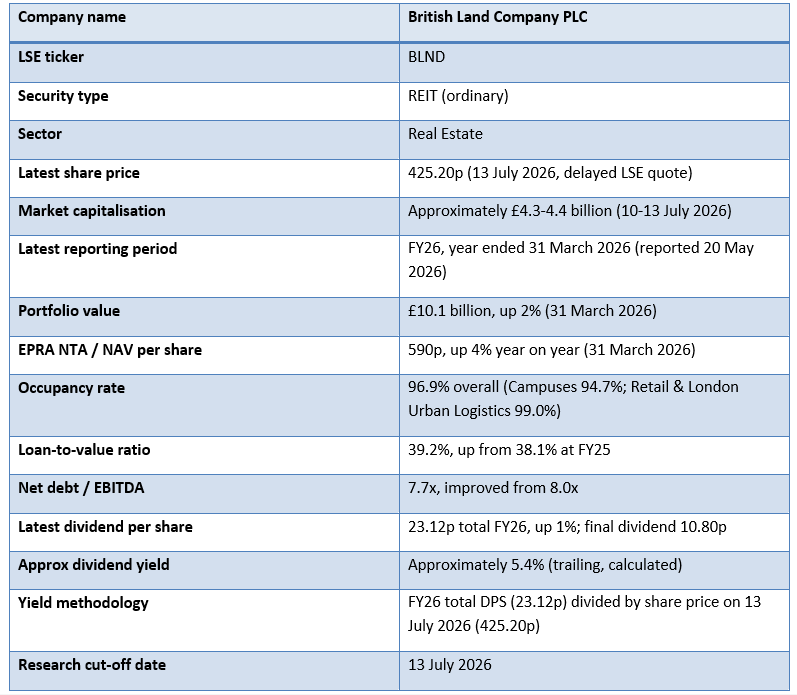
What does British Land own and do?
British Land is a FTSE 100-listed REIT that owns, manages and develops commercial property across three segments: London "campuses" (mixed-use office-led estates such as Broadgate, Regent's Place and Canada Water), retail parks, and London Urban Logistics assets. It recycles capital between segments toward the strongest rental growth.
As a REIT, British Land must distribute at least 90% of qualifying taxable property income to shareholders each year, in exchange for exemption from UK corporation tax on qualifying rental profits - a structural feature of the regime, not a guarantee of future dividend levels or growth.
Why is BLND attracting attention again?
Several threads have converged to put BLND back in focus. The FY26 results, published in May 2026, showed record leasing, rising campus rents and asset values moving higher for a second consecutive year, with some commentary linking improved office demand to AI-related occupier activity in London.
How did British Land perform financially in FY26?
For the year ended 31 March 2026, British Land reported underlying profit - its preferred earnings measure, broadly aligned with EPRA earnings - of £294m, up 5% from £279m in FY25. Underlying EPS rose 1% to 28.9p, and the company guided to FY27 underlying EPS of at least 30.5p.
EPRA NTA, the industry's standard net asset value measure, increased 4% to 590p per share as at 31 March 2026, up from 567p a year earlier. Total accounting return was 8.1% for the year and total property return was 7.4%. These are company-reported figures reflecting performance to the FY26 year-end, not forecasts.
How are the campuses, retail parks and logistics assets performing?
Portfolio valuation rose 2% over FY26 to £10.1bn. Overall occupancy stood at 96.9%, made up of 94.7% across campuses and 99.0% across retail parks and logistics. Like-for-like net rental growth was 6% group-wide, split between a strong 12% for campuses and 2% for retail and logistics; ERV growth was 4.9%.
Leasing totalled 3.8 million sq ft during the year, agreed 7.2% ahead of ERV, with a further 1.1 million sq ft under offer at 12.9% above ERV. British Land recycled capital, with £106m of disposals and £94m of new investment mainly in retail parks, and progressed a 1.6 million sq ft committed development pipeline on what it calls a "de-risked, capital-light" basis.
How strong is the balance sheet?
LTV rose to 39.2% as at 31 March 2026, up from 38.1%, while net debt/EBITDA improved to 7.7x from 8.0x. An absolute net debt figure was not confirmed in sources reviewed and is marked not verified; LTV and net debt/EBITDA are the confirmed leverage indicators here.
British Land raised £2.0bn of new finance during the year and held £1.6bn of undrawn facilities and cash at year-end, and says it has no refinancing requirement until early 2029. Its credit rating was maintained at 'A' by Fitch. At the half-year stage (30 September 2025), weighted average interest rate was 3.7%, predating the FY26 year-end.
What does the dividend look like?
British Land raised its total FY26 dividend by 1% to 23.12p, comprising a final dividend of 10.80p plus dividends already paid, including a reported interim of 12.32p for the six months to 30 September 2025. Growth of around 1% broadly tracked underlying earnings growth.
Against a share price of approximately 425p on 13 July 2026, the 23.12p dividend implies a trailing yield of roughly 5.4% - close to the original 5.46% screening yield, and well short of the threshold used here to flag a materially changed yield. As with any equity income, this dividend is not guaranteed and is set by the board each period.
What is happening in the wider UK property market?
British Land's FY26 numbers point to a UK commercial property market where London office demand - particularly for higher-quality campus space - has been recovering, with some commentary linking this to AI and technology-sector expansion. Retail parks continued to show high occupancy (99%), reflecting demand for out-of-town, logistics-adjacent space, even as rental growth there lagged campuses.
Sector commentary notes UK-listed property shares, including British Land, continue trading at wide discounts to net asset value amid UK political and macroeconomic uncertainty - improving fundamentals alongside a persistent valuation discount, a recurring theme across UK REITs.
Is BLND cheap or expensive relative to net asset value?
EPRA NTA stood at 590p per share as at 31 March 2026, while the shares traded at approximately 425p on 13 July 2026 - a discount to reported NAV of roughly 28%, a calculation from the company's own disclosures that moves as share price and NAV change.
Analyst commentary around the FY26 results also cited a forward price-to-book ratio of 0.59x against a stated ten-year average of 0.68x. British Land is often compared with Land Securities (Landsec) and logistics specialist SEGRO; wide NAV discounts have been a sector-wide feature, not a British Land-specific phenomenon.
What are the main risks for British Land?
Leadership transition is a near-term factor: incoming chief executive Joanne McNamara starts on 4 September 2026, replacing Simon Carter. Changes at the top can bring shifts in strategy or pace of execution, even where continuity is intended.
Analyst commentary around the FY26 results also flagged development execution risk on the pipeline, possible renewed build-cost inflation, and broader macroeconomic uncertainty. The rise in LTV to 39.2% and net debt/EBITDA of 7.7x mean the balance sheet carries more leverage than a year earlier, leaving less headroom if values or income disappoint. Past performance is not a guide to future results.
What might investors watch next?
Attention is likely to turn to the strategic priorities set once Joanne McNamara takes over in September 2026, and whether the campus-led growth and retail park recycling strategy continues largely unchanged. The next scheduled half-year update should show whether FY26's 12% campus rental growth and 96.9% occupancy are sustained.
Other points likely to feature include progress on the development pipeline, whether LTV stabilises after its rise to 39.2%, the pace of further disposals and acquisitions, and whether the gap between the share price and EPRA NTA narrows or persists.
Conclusion: a balanced view of BLND
The verified data as of 13 July 2026 shows a British Land that grew underlying profit, NAV per share and its dividend in FY26, with occupancy high and campus rents rising strongly. Leverage also increased over the period, and a chief executive transition is under way from September 2026. The roughly 5.4% trailing yield calculated here sits close to the original 5.46% screening figure.
None of the figures here should be read as a signal to buy, sell or hold British Land shares, nor as assurance about future dividends, NAV or share price performance. Readers considering the stock should consult British Land's full regulatory filings and seek independent financial advice.


 Nov 13, 2026





 Please wait processing your request...