
 CA
 NZ
 US
 AU
 IND

 UK

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Summary
Henry Boot PLC (LSE:BOOT) is a Yorkshire-based land promotion, property development and construction group. It is in focus after 2025 results showed record land sales but a 20% fall in pre-tax profit, alongside a 2.1% dividend increase to 7.86p. The shares near 164p yield about 4.7% and trade well below net asset value of 312p. The main catalyst is its land and development pipeline; the key risks are lumpy, second-half-weighted earnings and rising net debt.
Key takeaways
- Henry Boot's 2025 pre-tax profit fell about 20% to £26.4m on revenue of £251.5m, despite record land and property sales of £356m.
- The total 2025 dividend rose 2.1% to 7.86p per share; net asset value held at 312p.
- At about 164p the shares trade at roughly a 47% discount to NAV, with a trailing yield near 4.7%.
- Net debt increased to £108.0m and gearing to 25.7%, above the group's 10-20% target range.
- These ordinary shares (BOOT) are distinct from Henry Boot's fixed-rate preference shares (BD82): the ordinary shares carry growth and NAV exposure but a variable dividend.
Introduction
Henry Boot PLC (LSE:BOOT), the long-established Yorkshire land, development and construction group, has become a property-market talking point as investors weigh a resilient asset base against softer near-term earnings. At the research cut-off of 13 July 2026, the ordinary shares traded around 164p, giving a market capitalisation of about £226m and a trailing dividend yield near 4.7%. The screening snapshot quoted 4.97%, a figure that reflected a slightly lower share price; the headline is retained but the current yield is a little lower.
The focus follows Henry Boot's 2025 preliminary results, published on 24 March 2026, which paired record land and property sales with a roughly 20% drop in pre-tax profit and a small dividend increase. The story matters now because the group's earnings are inherently lumpy and second-half weighted, so investors are trying to gauge the underlying trajectory of a business trading at a wide discount to its stated net asset value.
Key facts 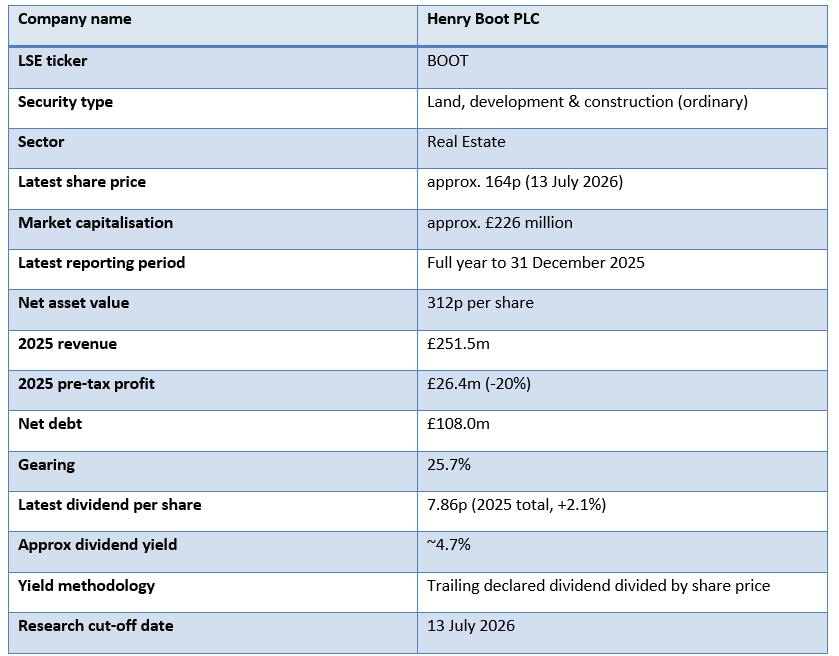
Company overview
Henry Boot operates through three complementary segments. Land promotion, via Hallam Land, secures planning permissions on strategic sites and sells consented land to housebuilders. Property investment and development, through HBD (Henry Boot Developments), builds and manages industrial, logistics, commercial and residential schemes. Construction comprises Henry Boot Construction, plant-hire business Banner Plant and the Road Link (A69) concession.
Why is BOOT attracting attention?
The stock stands out for the contrast between a solid, asset-backed balance sheet and a share price well below net asset value, combined with an above-average dividend yield for a developer. In 2025, Hallam Land delivered a record number of plot sales, underscoring demand for consented land even as overall profit fell.
Latest financial performance
For the year to 31 December 2025, Henry Boot reported revenue of £251.5m, down 8.9%, and pre-tax profit of £26.4m, down about 20% from £33.0m. Total land and property sales rose 2.6% to £356m, with Hallam Land achieving a record number of plot sales, showing the land business remained active even as margins and mix pressured profit.
For 2026, management said the group was well positioned to meet full-year market expectations, with consensus pre-tax profit around £20.2m, and cautioned that performance would again be second-half weighted given the timing of key transactions. That outlook is company guidance and explicitly assumes the conflict in the Middle East is not prolonged, a reminder that external events can affect delivery.
Land, development and construction activity
Henry Boot's value creation rests on moving land through the planning system and delivering development schemes. Hallam Land's record 2025 plot sales reflect continued housebuilder appetite for oven-ready sites, while HBD focuses increasingly on industrial and logistics development, a segment supported by structural demand.
The construction arm provides steadier, if lower-margin, activity and helps smooth the group's cash flows. The mix means Henry Boot is less a pure property landlord and more a developer-trader, so its pipeline of consented land and committed schemes, rather than a rent roll, is the key indicator of future earnings potential.
Balance sheet and debt (BOOT)
Net debt rose to £108.0m at the end of 2025 from £62.7m a year earlier, lifting gearing to about 25.7%, above the group's stated 10-20% target range. The increase reflects investment in land and development inventory ahead of future sales, which is normal for the model but worth monitoring.
Net asset value per share held steady at 312p, underpinning the equity. A developer-trader carrying higher debt is more exposed to a downturn in land or development markets, so investors will watch whether net debt moderates as schemes and land parcels are sold, and how comfortably interest costs are covered by cash generation.
Dividend analysis
Henry Boot raised its total 2025 dividend by 2.1% to 7.86p per share, continuing a long progressive record, with a final dividend of 4.62p. Against a share price of about 164p, that equates to a trailing yield of roughly 4.7%; at the lower price implied by the original screen the figure was nearer 4.97%.
The increase came despite a 20% fall in earnings, signalling management confidence, but it also means dividend cover tightened. With 2026 consensus profit lower, future increases may be more measured. The dividend is progressive rather than guaranteed and depends on the timing of land and development sales, so income investors should treat it as variable, not fixed.
How the ordinary shares differ from the BD82 preference shares
Henry Boot has two listed lines. The ordinary shares (BOOT) are equity: holders share in the group's growth, its 312p net asset value and a variable, progressive dividend, but rank behind creditors and preference holders. The preference shares (BD82) instead pay a fixed 5.25% coupon, rank ahead of the ordinary shares for income and capital, and offer no participation in NAV growth.
In short, the ordinary shares offer capital-growth potential and a higher but less certain payout tied to trading, while the preference shares offer a fixed, more defensive income. They suit different objectives, and their prices respond to different drivers, the ordinary shares to trading and property values, the preference shares mainly to interest rates and issuer creditworthiness.
UK land and development backdrop
The environment for Henry Boot mixes structural support with cyclical caution. The UK's housing shortage sustains demand for consented land, and logistics remains a favoured development sector, both positives for the land and HBD businesses. However, higher interest rates and construction-cost inflation can slow housebuilder land-buying and squeeze development margins.
Planning delays remain a perennial friction, affecting the timing of land sales, while domestic political and macroeconomic uncertainty can dampen developer confidence. These factors help explain why Henry Boot's earnings are volatile and why management stresses the second-half weighting of its results.
Valuation context
With the shares near 164p against net asset value of 312p, Henry Boot traded at roughly a 47% discount to NAV, and on a price-to-earnings ratio of about 10.5 times trailing profit. The discount is wide even by the standards of UK developers, reflecting the earnings decline and higher debt.
Main risks
Key risks include the lumpiness of land and development sales, which makes earnings volatile and heavily second-half weighted, and rising net debt and gearing above target, which increase sensitivity to a market downturn. A weaker housing or logistics market would slow land sales and pressure development margins.
Other risks include construction-cost inflation, planning delays, and macroeconomic or geopolitical shocks, which management explicitly flagged. The dividend, while progressive, could grow more slowly if profits stay subdued, and the wide discount to NAV may persist even if the underlying business performs steadily.
What investors may watch next
Investors are likely to focus on Henry Boot's half-year results for the six months to 30 June 2026, usually published in the autumn, for evidence of the expected second-half-weighted delivery against the roughly £20.2m consensus profit. Progress on Hallam Land plot sales, HBD scheme completions and construction activity will be central.
Balanced conclusion
Henry Boot enters 2026 as an asset-backed, conservatively managed developer trading at a wide discount to its 312p net asset value, with a progressive dividend yielding around 4.7% and a land business that set plot-sale records in 2025. Those attractions sit alongside a 20% earnings fall, lower 2026 profit guidance, and net debt that has risen above the group's target range.


 Nov 13, 2026





 Please wait processing your request...