
 CA
 NZ
 US
 AU
 IND

 UK

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Summary
CK Infrastructure Holdings (LSE:CKI, primary listing 1038.HK) currently trades on a dividend yield of roughly 4.3%-4.4%, based on its FY2025 total dividend of HK$2.61 per share (up from HK$2.58 in 2024). The final dividend of HK$1.88 was paid on 10 June 2026. The group recently completed the £4.2bn sale of its 40% UK Power Networks stake to Engie, a major structural shift for a company whose regulated UK, Australian and European utility assets have underpinned a multi-decade progressive dividend record, according to company filings reviewed on 13 July 2026.
Key takeaways
- CK Infrastructure's FY2025 total dividend rose 1.2% to HK$2.61 per share, continuing a long-running, though slowing, progressive payout trend.
- The trailing yield sits near 4.3%-4.4% depending on exchange, date and currency-conversion methodology used by different data providers.
- CKI completed the sale of its 40% UK Power Networks stake to Engie on 7 May 2026 for roughly £4.22bn, ahead of schedule.
- Net debt to net total capital stood at 8.9% on a company-only basis (48.5% look-through), with an S&P 'A' rating affirmed and a stable outlook.
- No special dividend has been confirmed; management says it will decide on use of disposal proceeds after the transaction fully settles, leaving real uncertainty for income investors.
Introduction
CK Infrastructure Holdings Limited (LSE:CKI, primary listing 1038.HK) is among the most internationally diversified regulated-utility groups accessible to UK income investors, via its London secondary listing in CREST Depositary Interests. As of this research, dated 13 July 2026, the group is navigating a pivotal year: it has just completed the disposal of a landmark UK electricity distribution asset while continuing a dividend record stretching back to its 1996 listing. This article examines the CK Infrastructure Holdings dividend yield story, alongside the group's financial position and key risks, for income-focused investors today.
Company overview
CK Infrastructure sits within the wider CK Hutchison/CK Group empire founded by the Li family, majority-controlled through CK Hutchison Holdings and CK Asset Holdings. It invests in and operates regulated and contracted infrastructure: energy transmission and distribution, water and gas networks, waste management and transport-related assets.
Its portfolio has historically included UK Power Networks (electricity distribution across London, the South East and East of England), Northumbrian Water, Northern Gas Networks and Eversholt UK Rails, plus assets in Australia, Continental Europe, New Zealand, Canada and Hong Kong/mainland China, per the 2025 annual results announcement via Investegate.
Two disposals have reshaped the group this year: Eversholt UK Rails was divested in January 2026, and the 40% UK Power Networks stake was sold to French utility Engie, with completion confirmed in May 2026 — nearly two months earlier than scheduled, per Utility Week.
CKI reports in Hong Kong dollars, and UK-based CDI holders on the London Stock Exchange receive dividends converted into pounds sterling at the exchange rate around each payment date — a detail that matters considerably when comparing yields across sources.
Latest dividend position (LSE:CKI)
CK Infrastructure's board proposed a final dividend of HK$1.88 per share with its FY2025 annual results, announced 18 March 2026, taking the full-year total to HK$2.61 — a 1.2% increase on 2024's HK$2.58, per the company's results statement and AJ Bell's coverage.
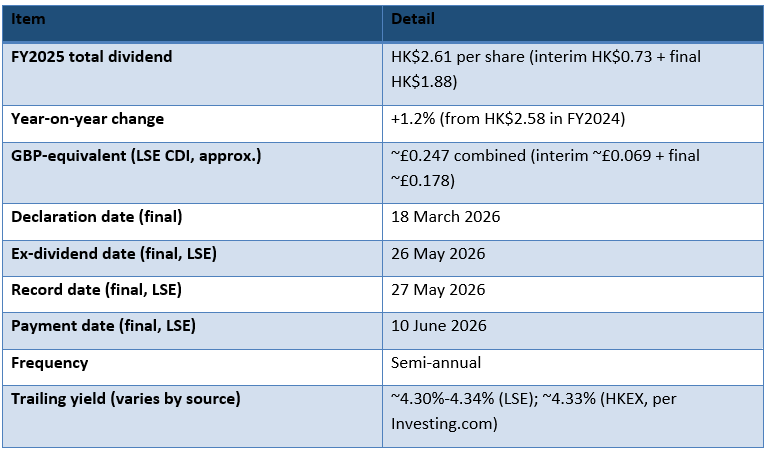
Because the final dividend has already been paid, today's quoted yield is trailing rather than a forward-looking promise. The next dividend decision follows interim results, which — based on the 13 August 2025 precedent — are likely to fall around mid-August 2026, after this article's cut-off, so any 2026 interim figure remains unconfirmed.
Dividend history
CK Infrastructure has built a reputation as a progressive payer since its 1996 Hong Kong listing, with Investing.com citing a run of consecutive annual increases stretching close to three decades. Recent growth, however, has been modest: dividend per share rose from HK$2.56 (2023) to HK$2.58 (2024) to HK$2.61 (2025), per the company's ten-year financial summary — low single-digit increases rather than the larger step-ups seen earlier.
This deceleration matters for the "why yields differ" question. Because sterling dividends for LSE CDI holders are set by the HKD/GBP rate at each payment date, a stronger or weaker pound between the interim and final payment can itself alter the GBP total received, independent of the Hong Kong dollar figure. That is one reason platforms report GBP dividend totals and yields that do not perfectly match.
Earnings and cash-flow analysis
FY2025 revenue reached HK$41,679 million, up 6.9% from HK$38,985 million, per the annual results filing. Profit attributable to shareholders rose 2% to HK$8,265 million, with EPS of HK$3.28 versus HK$3.22 — modest growth against higher revenue, reflecting margin and financing pressures typical of a capital-intensive utility portfolio.
Regional performance was uneven. Continental European operations delivered a standout 58% jump in attributable profit to HK$961 million, while Hong Kong and mainland China fell 48% to HK$68 million, and New Zealand grew 8.1% to HK$200 million, per AJ Bell.
Chairman Victor TK Li characterised the group's underlying momentum as organic growth across "many of the group's businesses" despite macroeconomic headwinds, per the results coverage. A specific consolidated free cash flow figure was not clearly itemised in the sources reviewed; the company noted cash on hand of HK$7.4 billion at year-end, though a precise dividend cover ratio versus free cash flow could not be independently verified from public sources at time of writing.
Balance-sheet analysis
Net assets stood at HK$137.9 billion at 31 December 2025, up 5.0% year-on-year. Net debt to net total capital was 8.9% on a standalone basis, rising to 48.5% on a "look-through" basis that incorporates the group's proportionate share of debt held within jointly controlled and associate businesses — common where operating debt sits at asset level.
S&P Global Ratings affirmed CK Infrastructure's 'A' issuer rating with a stable outlook, alongside sister company Power Assets Holdings, reflecting confidence in its diversified, largely regulated cash-flow base. The UK Power Networks disposal, completed in May 2026 for roughly £4.22 billion (about HK$44.3 billion), is expected to strengthen liquidity materially, with an anticipated accounting gain near HK$14.5 billion, per The Standard and the company's results statement.
Company-specific growth drivers
The UK Power Networks sale is the dominant near-term story. Deputy Managing Director Andrew Hunter was quoted saying the board would "consider the matter" of using proceeds only "after the transaction is completed," while stressing that "cash is king" in a volatile market and that a stronger cash position offers "greater flexibility and opportunities" — language signalling optionality rather than a committed special dividend.
Beyond the disposal, growth drivers include continued expansion of Continental European operations, which posted the group's strongest profit growth in FY2025, and ongoing investment in regulated UK water and gas networks (Northumbrian Water, Northern Gas Networks) that benefit from inflation-linked regulatory frameworks, subject to periodic price control reviews by Ofwat and Ofgem.
Industry and economic backdrop
Regulated utility owners like CK Infrastructure operate in a sector shaped by interest rates, inflation-linked revenue mechanisms and regulatory settlements. Higher-for-longer rates globally have raised financing costs across this capital-intensive sector, a headwind partly offset by inflation-linked allowed returns in frameworks such as the UK's RIIO price controls.
The scale of the Engie-UK Power Networks transaction — a total consortium deal value cited at £16.84 billion, with Engie reportedly financing the purchase through debt, hybrid instruments and asset disposals — underscores continued strategic investor appetite for UK regulated infrastructure despite broader macro uncertainty, per LexisNexis legal news coverage of the deal structure.
Valuation and share-price context (no recommendation)
CK Infrastructure shares traded around HK$59.70 in Hong Kong as of 30 June 2026, per Investing.com, implying a P/E near 18x on that platform's trailing basis, against a 52-week range of roughly HK$50.20 to HK$67.90. On the London listing, CDI prices have recently sat between 564p and 582p, with stockanalysis.com citing 574.00p on 10 July 2026 and AJ Bell citing a P/E near 17.2x and market capitalisation of about £14.4-14.5 billion.
These figures show why headline yields vary by source: P/E estimates range from roughly 15.8x (forward, Stockopedia) to over 18x depending on whether trailing or forward earnings are used, which price snapshot is taken, and how HKD is converted to GBP. This article's supplied starting-reference yield of approximately 4.32% sits within the independently verified range (4.30%-4.34%), suggesting a reasonably current snapshot rather than a stale figure. No view is offered here on whether the shares are cheap or expensive relative to peers such as Power Assets Holdings or National Grid; cross-currency, cross-exchange comparisons warrant caution.
Main risks
A high dividend yield can reflect either an attractive income opportunity or elevated risk, where the market has marked down the shares or a payout may be harder to sustain. Several risks are specific to CK Infrastructure.
First, currency risk: HKD dividends translated into GBP for LSE CDI holders are exposed to exchange-rate swings between declaration and payment, so the sterling dividend and yield can move even if the HKD figure is unchanged.
Second, the loss of UK Power Networks removes a substantial regulated cash-flow contributor; while proceeds boost liquidity, replacing that recurring income carries execution risk, and returns on redeployed capital are not guaranteed.
Third, regulatory and interest-rate risk remains material across all jurisdictions, particularly given upcoming UK and Australian price reviews and the sensitivity of utility valuations to borrowing costs.
Fourth, no dividend — however long its record — is guaranteed; CKI's own payout growth has slowed to roughly 1% annually, and future increases depend on earnings, regulatory outcomes and board discretion.
What investors may watch next
Interim 2026 results, likely around mid-August 2026 based on the prior 13 August 2025 date, should confirm whether an interim dividend increase continues and may clarify how UK Power Networks proceeds will be deployed — including any special distribution, buyback or reinvestment. Developments in European growth markets and any further disposals or acquisitions also warrant monitoring.
LSE:CKI dividend sustainability in focus
Given the scale of change to CKI's asset base this year, management's dividend-sustainability commentary at the next results update will be particularly important for LSE:CKI income investors to assess.
Balanced conclusion
CK Infrastructure Holdings offers exposure to a broad, largely regulated global infrastructure portfolio with a multi-decade dividend history and, following the UK Power Networks disposal, a strengthened cash position and an affirmed 'A' credit rating. The trailing yield of roughly 4.3%-4.4% appears within a normal range rather than a distress signal.
That said, dividend growth has slowed to roughly 1% annually, currency translation adds complexity for UK-based CDI holders, and the loss of a major regulated UK asset introduces genuine uncertainty about how capital will be redeployed. Prospective investors should treat the current yield as a snapshot of a company in transition, not a fixed or assured future income stream, and watch the August 2026 interim results closely for further clarity.
Top of Form
Bottom of Form


 Nov 13, 2026





 Please wait processing your request...