.png)
Telford Homes
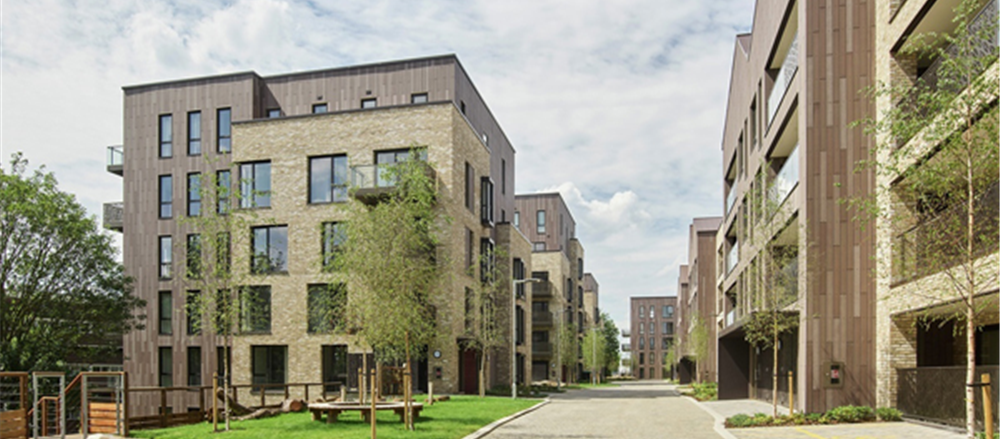
Telford Homes PLC (TEF) is a developer of residential-led, mixed-use sites in London, and is one of London's largest residential developers. The group focuses on brownfield opportunities in locations across London, with customers ranging institutional to individual investors and owner-occupiers and housing associations. Jon Di-Stefano is the Chief Executive Officer.
Recent Development
On 5 March 2019, the company announced that M&G Real Estate and Invesco Real Estate had been chosen as its long term strategic build-to-rent partners, with M&G chosen as the priority partner for projects including up to 200 build-to-rent homes and Invesco for more than 200. The partnership would shorten and improve the contractual process for each transaction as it would help to produce a standard set of documents for forward fund development and would lead to more efficient ways of buying land and designing build-to-rent schemes that match up with each investor's requirements.
Key Financial Highlights (FY 2019, in £m)
Despite a challenging economic and political environment, the company reported a rise in total revenue to a record high of £354.3 million from £316.2 million last year, driven by an increase in revenue from build-to-rent contracts. Gross profit on a GAAP basis was £75.0 million, and total gross profit was is in line with the prior year at £79.3 million. Adjusted gross margin declined to 23.7 per cent as compared to 26.5 per cent recorded last year. Due to lower gross margin and an increase in sales costs as a proportion of revenue, adjusted operating margin also declined to 13.1 per cent (2018: 16.7 per cent). GAAP profit before tax was £40.3 million (2018: £46.3 million), while total profit before tax has reduced to £40.1 million (2018: £46.0 million). Earnings per share were 44.6 pence for the year, against 49.8 pence last year. The company proposed a final dividend of 8.5 pence per share, which together with the interim dividend of 8.5 pence, helped to maintain the total dividend for the year at 17.0 pence per share.
Valuation Methodology
Method: Price/Earnings Approach (NTM)
.png)
Share Price Commentary
.png)
Daily Chart as at May-30-19, before the market closed (Source: Thomson Reuters)
On 30 May 2019, at the time of writing (before the market closed, GMT 11:05 am), TEF shares were trading at GBX 293.00, up by 1.4 per cent against the previous day closing price. Stock's 52 weeks High and Low is GBX 469.06/GBX 260.00. The company's stock beta was 0.89, reflecting less volatility as compared to the benchmark index. Total outstanding market capitalisation was around £219.80 million, with a dividend yield of 5.89 per cent.
Conclusion
With an increased focus on lower risk and less capital-intensive build-to-rent developments, the company expects profit to grow again and the output of build-to-rent homes to increase. This will help in delivering high-quality rental properties in the capital and meet demand from institutional investors. The proportion of Londoners renting is rising, and the rental market is undersupplied with issues like poor quality houses. Purpose-built rental housing assists in addressing these issues, which presents a significant growth opportunity for the company and augurs well for its future.
While build-to-rent transactions generate lower margins and this has resulted in absolute profits to fall, the company was successful in reducing gearing to 37.0 per cent at 31 March 2019 from 52.2 per cent at 30 September 2018. This was because of increased exposure to less capital intensive and lower risk developments. Based on a decent financials and supported by valuation done using the above method, we have given a “SPECULATIVE BUY” recommendation at the closing price of GBX 288.50 (as on 29th May 2019) with a single digit-upside potential based on 12.05x NTM Price/Earnings (approx.)on FY20E earnings per share (approx.).
Synnovia Plc
Synnovia PLC (SYN) is a niche developer and producer of specialist products, including High Strength Film Packaging, Specialist Sacks and Pouches and Industrial Consumer Components, with a wide range of applications. Synnovia has a well-established international network which enables it to sell to over 80 countries worldwide either directly or through distributors. The company's operations are differentiated in two segments: Films and Industrial.
Key Financial Highlights (H1 FY2019)
.png)
Source: Interim Results, Company Website
In the first half of FY2019, revenue rose by 11.4% to £40.6 million, representing organic growth of 12.1% at constant currency. Group’s EBITDA rose by 42.8% at actual currency rates to £3.6 million, led by strong balanced growth across the two divisions, while it was up by 29.0% at constant currency driven mainly by Industrial Division. Reflecting the gearing of the business, earnings per share were increased by 67.9% to 4.7 pence and profit before tax was up by 75.4% to £2.1 million. The board did not propose any dividend, citing opportunities for growth and rate of return.
Valuation Methodology
Method: Price/Earnings Approach (NTM)

Share Price Commentary

Daily Chart as at May-30-19, before the market closed (Source: Thomson Reuters)
On 30 May 2019, at the time of writing (before the market closed, GMT 11:55 am), SYN shares were trading at GBX 87.50 and remained flat against the previous day closing price. Stock's 52 weeks High and Low is GBX 121.00/GBX 84.40. The company's stock beta was 1.10, reflecting more volatility as compared to the benchmark index. Total outstanding market capitalisation was £34.19 million.
Conclusion
The company has set a new five-year target to achieve £15 million EBITDA by end FY23-24, improving its older target to achieve £10.5 million EBITDA by FY 2020, driven by a strong growth rate in revenue and profit. The company’s businesses benefit from operating in niche markets in which they provide superior products and technical expertise, which is supported by continuous development and introduction of innovative products. This provides further opportunities for revenue growth and additional profit and has the potential to maintain this rate of growth and profitability over the long run.
Based on a decent prospect and supported by valuation done using the above method, we have given a “SPECULATIVE BUY” recommendation at the closing price of GBX 87.50 (as on 29th May 2019) with a single digit-upside potential based on 9.90x NTM Price/Earnings (approx.)on FY19E earnings per share (approx.).
*The “Speculative Buy” recommendation is also valid for the current price as covered in the report (as on May-30-19)
*All forecasted figures and peers have been taken from Thomson Reuters.
Disclaimer
PLEASE BE ADVISED THAT YOUR CONTINUED USE OF THIS SITE OR THE INFORMATION PROVIDED HEREIN SHALL INDICATE YOUR CONSENT AND AGREEMENT TO THESE TERMS.
References to ‘Kalkine’, ‘we’, ‘our’ and ‘us’ refer to Kalkine Limited.
This website is a service of Kalkine Limited. Kalkine Limited is a private limited company, incorporated in England and Wales with registration number 07903332.
The article has been prepared for informational purposes only and is not intended to be used as a complete source of information on any particular company. Kalkine is not responsible for material posted on this website and does not guarantee the content, accuracy, or use of the content in this site. No advice or information, whether oral or written, obtained by you from Kalkine or through or from the service shall create any warranty not expressly stated.
Kalkine do not offer financial advice based upon your personal financial situation or goals, and we shall NOT be held liable for any investment or trading losses you may incur by using the opinions expressed in our publications, market updates, news alerts and corporate profiles. Kalkine does not in any way endorse or recommend individuals, products or services that may be discussed on this site. You should discuss your portfolios and the risk tolerance level appropriate for your personal financial situation, with a professional licensed financial planner and adviser.

 CA
 NZ
 US
 AU
 IND

 UK
 Please wait processing your request...