
Hurricane Energy
Hurricane Energy PLC (HUR) is an oil and gas exploration and development company that discovers, appraises and develops hydrocarbon resources from fractured basement reservoirs. The company has licenses focussed on the Rona Ridge and owns a portfolio of offshore licences on the UK Continental Shelf. Dr Robert Trice is the Chief Executive Officer of the group.
Operational Update
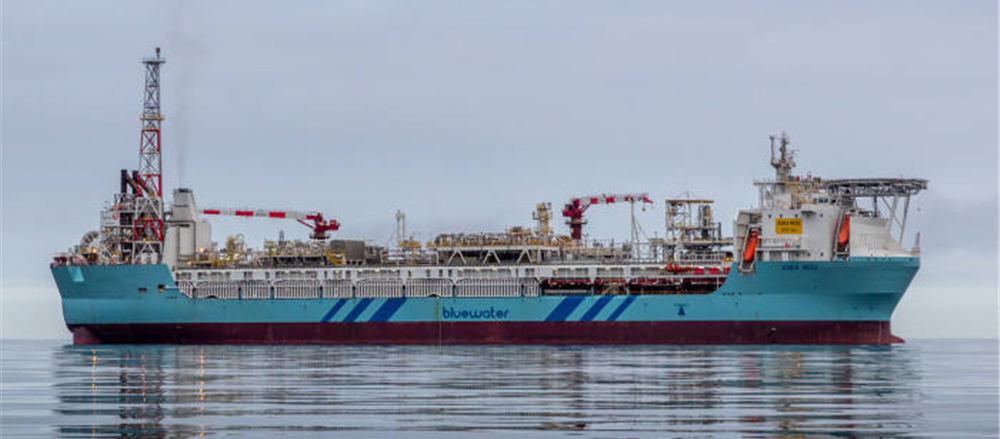
On 5th June 2019, the company announced that the Lancaster field was now on production and the first oil had been produced from one of its fields there. The company said that it had completed a 72-hour production test of two wells at its Lancaster field and reported that both the wells maintained a production rate of 20,000 barrels of oil a day in the test.
Financial Highlights (FY2018, $m)
The company’s reported operating loss decreased from $25 million in FY17 to $12.7 million in FY18. The Group’s loss after tax for the year 2018 stood at $60.9 million and increased significantly against the loss of $7.0 million reported in 2017, due to an increase in non-cash fair value loss on derivative financial instruments of $42.4 million associated with Hurricane’s convertible bonds.Thetotal comprehensive loss for the year surged from $7 million in 2017 to loss of $59.1 million in 2018. The basic and diluted loss per share rose from 0.46 cents in the financial year 2017 to 3.11 cents in FY2018. The net cash position stood at $123.2 million at the end of FY2018.
Valuation Methodology
Method: Price/Earnings Approach (NTM)

Share Price Commentary

Daily Chart as at June-06-19, before the market closed (Source: Thomson Reuters)
On 6th June 2019, at the time of writing (before the market closed, GMT 4:05 pm), HUR shares were trading at GBX 56.4, up by 0.7 per cent against the previous day closing price. Stock's 52 weeks High and Low is GBX 64.70/GBX 38.00. The company's stock beta was 1.55, reflecting more volatility as compared to the benchmark index. Total outstanding market capitalisation was £1.1 billion.
Conclusion
The company is hoping to be the first companyto prove that oil can be commercially produced from fractured basement rock formations in UK waters and if it is able to prove production is sustainable at the Lancaster field, then it is likely to attract the interest of oil majors. For the first three months, the group plans to produce an average of 9,000 barrels per day, which is planned to increase to 13,000 for the next three, demonstrating the scale and deliverability of its production. However, to fully understand the scale of the reservoir and sustainability of production, the market required nine to 12 months of production data from now.
Based on healthy prospects and supported by valuation done using the above method, we have given a "BUY" recommendation at the closing price of GBX 56.15 (as on 5th June 2019) based on 41.50x NTM Price/Earnings (approx.) on FY19E earnings per share (approx).
Premier Oil
Premier Oil PLC (PMO) is a London, United Kingdom-headquartered international oil and gas production and exploration group. As opposed to the 'downstream' refining and retail sector, the company is entirely engaged in the 'upstream' sector of the industry – the exploration and production of oil and gas. The group has a high-quality portfolio of the company which provides it with organic growth opportunities. The company has oil and gas interests in the Falkland Islands, the North Sea, Latin America, and South East Asia. The company's operations are differentiated according to five geographical segments: the Falkland Islands, the United Kingdom, Vietnam, Indonesia, and the Rest of the World.
Trading and Operations Update (1 Jan to 15 May 2019)
Year to date production increased by 14% on the prior year corresponding period to 85.1 kboepd, which was significantly ahead of expectations. While guidance for opex and capex remained unchanged, 2019 full year production guidance increased to 75-80 kboepd, extending the top of the range from 75 kboepd. The company successfully reduced its net debt to $2.25bn, driven by free cash flow generation of around $80 million. It anticipates achieving the upper range of $250m to $350m guidance for net debt reduction, with a covenant leverage ratio of less than 2.3x.
Key Financial Highlights (2018, in $m)

(Source: Company Filings)
Total revenue from all operations, which includes Pakistan, increased from $1,102 million reported in 2017 to $1,438.3 million in 2018, while revenue from continuing operations (excluding Pakistan) rose to $1,397.5 million from $1,043.1 million in 2017.Due to higher production and realised prices during the year, EBITDAX for 2018 from continuing operations surged by 50 per cent to $882.3 million. Net Profit stood at $133.4 million, rising from a loss of $253.8 million reported in 2017. This resulted in a basic EPS of 17.3 cents, versus a loss of 49.4 cents in 2017, reflecting an increase in sales revenue and the subsequent impact on operating profits.
Valuation Methodology
Method: Price/Earnings Approach (NTM)

Share Price Commentary

Daily Chart as at June-06-19, before the market closed (Source: Thomson Reuters)
On 6th June 2019, at the time of writing (before the market closed, GMT 4:10 pm), PMO shares were trading at GBX 73.83, up by 0.6 per cent against the previous day closing price. Stock's 52 weeks High and Low is GBX 146.90/GBX 54.70. The company's stock beta was 3.51, reflecting significantly higher volatility as compared to the benchmark index. Total outstanding market capitalisation was £605.79 million.
Conclusion
In the latest update, the company reported that it continues to deliver ahead of plan, with the group upgrading its production guidance. The group is reducing debt faster than anticipated, helped by higher than forecasted production and free cash flow. The company is also making good progress on its growth projects and the Tolmount East appraisal well is due to be tested in July. The Tolmount project is the next significant growth project in the pipeline and once production reaches the peak rate, it is expected to yield some 58 kboepd. The low-cost base and a disciplined Capex programme undertaken by the group has resulted in strong operational performance and will further help in generating material free cash flow.
Based on healthy financials and supported by valuation done using the above method, we have given a "BUY" recommendation at the closing price of GBX 73.42 (as on 5th June 2019) based on 9.82x NTM Price/Earnings (approx.) on FY19E earnings per share (approx.).
*All forecasted figures and peers have been taken from Thomson Reuters.
*The Buy recommendation is also valid at the current price as on June-06-19.
Disclaimer
PLEASE BE ADVISED THAT YOUR CONTINUED USE OF THIS SITE OR THE INFORMATION PROVIDED HEREIN SHALL INDICATE YOUR CONSENT AND AGREEMENT TO THESE TERMS.
References to ‘Kalkine’, ‘we’, ‘our’ and ‘us’ refer to Kalkine Limited.
This website is a service of Kalkine Limited. Kalkine Limited is a private limited company, incorporated in England and Wales with registration number 07903332.
The article has been prepared for informational purposes only and is not intended to be used as a complete source of information on any particular company. Kalkine is not responsible for material posted on this website and does not guarantee the content, accuracy, or use of the content in this site. No advice or information, whether oral or written, obtained by you from Kalkine or through or from the service shall create any warranty not expressly stated.
Kalkine do not offer financial advice based upon your personal financial situation or goals, and we shall NOT be held liable for any investment or trading losses you may incur by using the opinions expressed in our publications, market updates, news alerts and corporate profiles. Kalkine does not in any way endorse or recommend individuals, products or services that may be discussed on this site. You should discuss your portfolios and the risk tolerance level appropriate for your personal financial situation, with a professional licensed financial planner and adviser.

 CA
 NZ
 US
 AU
 IND

 UK
 Please wait processing your request...