.png)
Trans-Siberian Gold
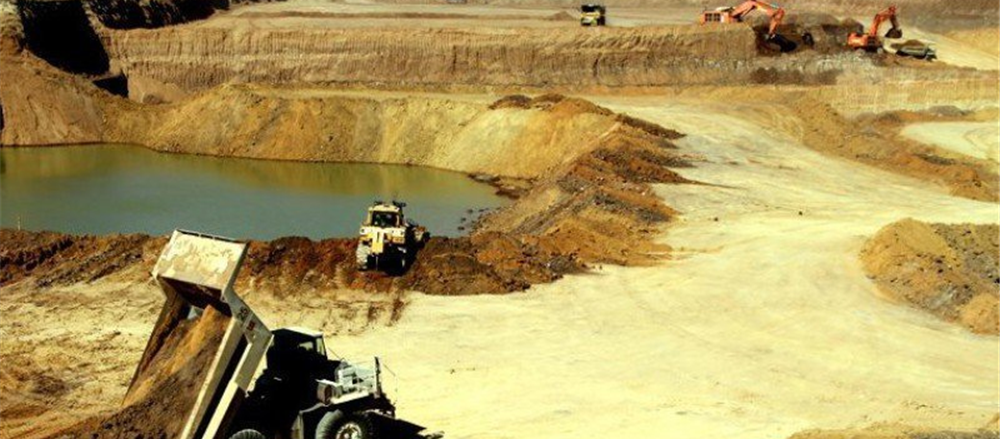
Trans-Siberian Gold PLC (TSG) is a Cambridge, United Kingdom-headquartered holding company which is engaged in gold production, development and exploration in Russia. The company fully owns the Asacha Gold Mine, which is located in Kamchatka in Far East Russia and is an established gold mine with high-grade underground operation. The company focuses on low cost, high-grade mining operations with stable gold production and generally sells the gold produced to Russian commercial banks.
Production Update
The company during the three months ended 30 June 2019, in the second quarter, reported that gold production remained stable at 9,544 oz (Q2 2018: 9,260oz), while gold production for the first half of 2019 rose by 26% to 21,889 oz, indicating that the company was in line to achieve full year production of 40-44,000 oz. The group reported a 33% increase in average quarterly gold grade at 8.4 g/t (Q2 2018: 6.3g/t) and 39% increase to 8.6 g/t for the first half, as it continues to target higher grades. Silver production during the quarter remained largely unchanged at 27,629 oz while it reported an increase of 42% in silver production to 59,787 oz in the first half. Total Q2 revenues rose by 14.7% to $13,761,000, driven by 442.8% increase in silver revenue to $484,000 and 11.5% increase in gold revenue to $13,276,000. Reflecting a strong second quarter, the company reported record revenue of $29,998,000 in the first half, up by 8.6% over the year.
Financial Highlights (FY 2018, in $m)
Driven by 36% increase in sales of gold to $58.2 million (2017: $42.7 million) and a 100% increase in sales of silver to $1.6 million (2017: $0.8 million), the company reported revenue rose by 38% over the year to $59.8 million (2017: $43.4 million), a record-breaking amount for the group. The company recorded an operating profit for the year of $18.0 million (2017: $4.3 million) and reported a 72% increase in EBITDA at $23.9 million (2017: $13.9 million). Profit before tax was $17 million (2017: $3.0 million) and profit for the financial year was reported at $12.5 million, against $2.5 million in 2017. Earnings per share amounted to 11.3 cents, and the group proposed a final dividend of $0.009 cents per share (2017: $0.021).
Valuation Methodology
Method: Price/Earnings Approach (NTM)
.png)
Share Price Commentary
.png)
Daily Chart as at 02-August-19, before the market closed (Source: Thomson Reuters)
On 02 August 2019, at the time of writing (before the market closed, GMT 12:35 am), TSG shares were trading at GBX 86.84, up by 5.26 per cent against the previous day closing price. Stock's 52 weeks High and Low is GBX 88.90/GBX 29.43. The company's stock beta was 1.37, reflecting more volatility as compared to the benchmark index. Total outstanding market capitalisation was around £72.06 million, with a dividend yield of 1.74%.
Conclusion
As ore extracted and processed during 2018 was 173,597 and 189,695 tonnes respectively against an annual capacity of 150,000 tonnes, the flagship Asacha plant has continued to deliver well above its capacity, and average gold recovery also remained strong. The company remained committed to an attractive and stable dividend pay-out and had become one of the highest yielding mining stocks on the exchange, with two dividend payments during 2018 amounting to approximately $6.7 million. The company has expanded its portfolio through the acquisition of Rodnikova and continues to reduce costs and optimise operational efficiency. While the all-in sustaining costs per oz gold was $1,049 (2017: $1,341), cash cost per oz gold sold was $516 (2017: $588), indicating better efficiency. Central banks have been buying gold at a record rate, and Russia was the largest purchaser of gold in 2018, which augurs well for the company. However, factors like political and economic conditions of major gold-producing countries, industrial and jewellery demand, global and regional economic and political events, world production levels influence the gold price, which is not in the control of the company. Moreover, the share is trading near the 52-week high, demanding a need for caution.
Based on the above risk factors, and supported by valuation done using the above method, we have given a "WATCH" recommendation at the current price of GBX 86.84 (as on 02 August 2019) based on 8.47x NTM Price/Earnings (approx.) on FY19E Earnings per share (approx.), while we look for upcoming catalysts in near term.
*Peers of the company are Serabi Gold PLC, Shanta Gold Ltd, Polyus PAO, Chaarat Gold Holdings Ltd
*All forecasted figures and peers have been taken from Thomson Reuters.
Bacanora Lithium
Bacanora Lithium PLC (BCN) is a London-headquartered, AIM-listed lithium development company, which seeks to commercialise the Sonora Lithium Project in Mexico and develop the next major lithium project in the country. The group is one of the few pure-play lithium development groups listed on the London Stock Exchange. A feasibility study of the Sonora Lithium Project confirmed favourable operating costs and positive economics, with an internal rate of return of 26.1% and pre-tax project net present value of $1.253 billion. The operations of the company are differentiated in three segments, namely Mexico, Germany and Head Office.
Recent Development
The company on 28 June 2019 announced the signing of Investment Agreement and Offtake Agreement with Ganfeng Lithium, which would result in Ganfeng acquiring 29.99% of Bacanora and 22.5% of Sonora Lithium Ltd, the holding company for the Sonora Lithium Project. Ganfeng Lithium is the third-largest lithium compounds producer in the world and the largest lithium metals producer in terms of production capacity, and the competition of the agreement would form a major part of the financing for an initial lithium carbonate operation at Sonora Project in Mexico. The company on 1 August 2019 announced that the first approval from the Chinese Ministry of Commerce had been received and the company is awaiting the rest two approvals.
Financial Highlights (H1 FY 2019, in $m)
As the company continues to strengthen its management and operations teams in preparation to advance into development and construction, general and administrative costs increased by $1.5 million, which resulted in operating loss of $4.4 million as compared with a loss of $3.2 million in H1 FY 2018. The group incurred finance costs of $2.1 million and the group reported costs related to completion and maintenance of debt financing. Property, plant and equipment rose to $29.2 million at the end of the period from $26.4 million at 30 June 2018, while current liabilities reduced by $6 million due to the settlement of accounts payable. The total net assets of the group declined to $38.9 million at 31 December 2018 ($42.6 million at 30 June 2018), while closing cash balance of the group was $20.5 million at the end of December 2018 ($13.2 million at 30 June 2018).
Share Price Commentary
.png)
Daily Chart as at 02-August-19, before the market closed (Source: Thomson Reuters)
On 02 August 2019, at the time of writing (before the market closed, GMT 10:35 am), BCN shares were trading at GBX 45.40, up by 0.88 per cent against the previous day closing price. Stock's 52 weeks High and Low is GBX 64.00/GBX 11.55. The company's stock beta was 1.29, reflecting more volatility as compared to the benchmark index. Total outstanding market capitalisation was around £60.64 million.
Conclusion
Driven by the automotive industry and renewable battery storage, demand for lithium is slated to increase in future, with the global lithium-ion battery market anticipated to rise from $17.5 billion to $70 billion by 2020. The company is confident of becoming a major supplier of high-value battery-grade lithium products, backed by high-quality projects, which produces lithium that does not require considerable high-cost beneficiation to upgrade to battery-grade quality. As the estimated cost of operation at the flagship project would be one of the lowest-cost producers in the industry, the production of a 35,000 tonnes per annum lithium carbonate would be undertaken at low cost. However, as the lithium market matures, short term shocks can be expected, like increase in production from other producers or cooling demand in China, which might result in a volatile price of battery-grade lithium carbonate in the market.
On the basis of above rationale, we recommend investors to “HOLD” the stock at the closing price of GBX 45.00 as on 01-August-19.
Disclaimer
PLEASE BE ADVISED THAT YOUR CONTINUED USE OF THIS SITE OR THE INFORMATION PROVIDED HEREIN SHALL INDICATE YOUR CONSENT AND AGREEMENT TO THESE TERMS.
References to ‘Kalkine’, ‘we’, ‘our’ and ‘us’ refer to Kalkine Limited.
This website is a service of Kalkine Limited. Kalkine Limited is a private limited company, incorporated in England and Wales with registration number 07903332.
The article has been prepared for informational purposes only and is not intended to be used as a complete source of information on any particular company. Kalkine is not responsible for material posted on this website and does not guarantee the content, accuracy, or use of the content in this site. No advice or information, whether oral or written, obtained by you from Kalkine or through or from the service shall create any warranty not expressly stated.
Kalkine do not offer financial advice based upon your personal financial situation or goals, and we shall NOT be held liable for any investment or trading losses you may incur by using the opinions expressed in our publications, market updates, news alerts and corporate profiles. Kalkine does not in any way endorse or recommend individuals, products or services that may be discussed on this site. You should discuss your portfolios and the risk tolerance level appropriate for your personal financial situation, with a professional licensed financial planner and adviser.

 CA
 NZ
 US
 AU
 IND

 UK
 Please wait processing your request...