
PayPoint Plc (PAY)
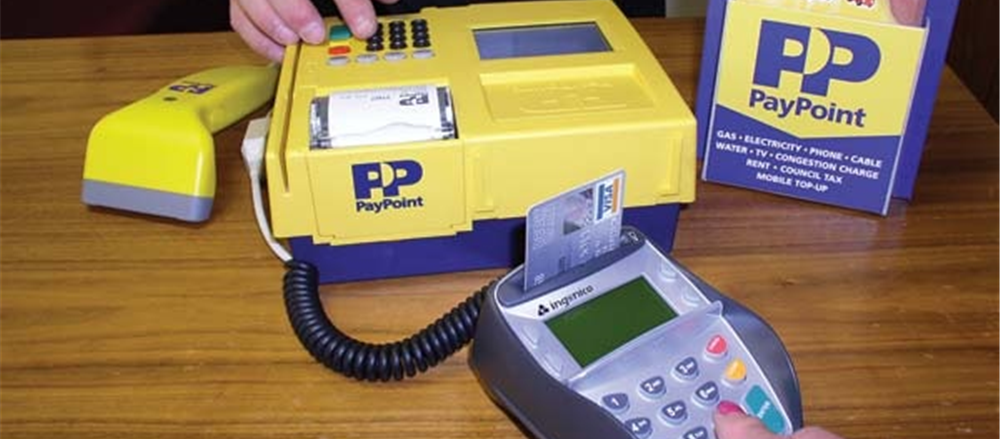
PayPoint Plc is a United Kingdom-headquartered holding company. Through its subsidiaries, the group offers specialist consumer payment, and other services and products and transaction processing and settlement. Its specialist product and services are PayPoint One/ EPoS, Collect+, MultiPay, eMoney, Card payment and ATMs.Shares of the company got listed as on September-24-2004 on the main market of the London Stock Exchange for trading. Liontrust Investment Partners LLP, Woodford Investment Management Ltd., Capital Research & Management Co. (Global Investors), Standard Life Investments Ltd. and FIL Investment Advisors (UK) Ltd. are some of the major institutional investors in the group. Institutional investors hold around 62.67% of the total equity (Source: Thomson Reuters).
Recent Development
In the exchange filing made by the company as on June-28-2019, the group has notified that after extensive negotiation with British Gas, the group was unable to decide a suitable renewal terms with British gas for multi-year contracts and after December-31-2019, the group will cease working with British Gas.
It would dent the group's revenue for the FY20 by approximately £1.4 mn, and for the financial year 2021, it would impact approximately £3.5 mn of the group's revenue.
Financial Performance: FY19
During the year under consideration, the group's underlying revenue recorded a growth of 1.6%. However, reported revenue slumped by 0.9% to £211.6mn, on account of closure of the Simple Payment Services (SPS) that dented approximately £5.2mn and renegotiations of the Yodel contract. For the financial year FY19, the group’s underlying net revenue surged by £2.2 mn or 2%, mainly because of the roll-out of Pay Point One and improvement in Multipay, eMoney and Romania’s transactions. However, reported net revenue narrowed by 2.5% or £3.0mn to £116.6 mn on account of closure of Simple Payment Services. Pre-tax profit of the group, excluding exceptional items surged to £53.8 mn against £52.9 mn in FY18 and recorded a growth of 1.6% on a YoY basis. At the end of the financial year FY19, net corporate cash stood at £3.5 mn, and approximately £75mn financing facilities was unutilised.
The Board of the company has announced a final dividend of 23.6 pence per share, and including the final dividend, the full-year ordinary dividend for the FY19 stood at 46.2 pence per share against 45.3 pence per share in the year-ago period. However, the group has committed to pay an additional dividend of £25 mn per annum till December 2021 along with the ordinary dividend.
Stock Performance

Daily Price Chart (as on July 09, 2019), before the market close. (Source: Thomson Reuters)
At the time of writing (as on July 09, 2019), shares of the PayPoint Plc were quoting at GBX 925 and declined marginally against the previous trading session. In the year-ago period, its shares have registered a 52w high price of GBX 1,158.0 and a 52w low of GBX 721.98 respectively. On a year-to-date basis, the stock has delivered a price return of 14.71%. However, in the past 1-month, the share was down by 11.6%.
Valuation Methodology

Conclusion
The company’s reported performance was decent in FY2019 period and was driven by sales growth in the PayPoint One, MultiPay and Romania, resilience in bill payments and strong cost control. The improvement in the before-tax profit was achieved despite significant revenue headwinds from the DWP SPS service (£4.2 million) service closure. For the group to report decent performance in FY20, it requires revenue improvement in PayPoint One, Multipay, Parcels and Romania, as the group has scaled up its new partnerships, continued resilience in bill payments as well and cost control. Also, despite recent revenue headwinds, the group has witnessed growth during the previous financial year, and the Board is confident that pre-tax profit for the year ending March 31, 2020, will show progression.
Therefore, based on the above discussion and valuation done using the above methodology, we have given a "Speculative Buy" recommendation on the stock, at the closing price of GBX 928.0 (as on July-08-2019), with single-digit upside potential, based on the 13.2x NTM Price-to-Cash Flow per share (approx.) on the FY20E Cash flow per share (approx.).
Provident Financial Plc (PFG)
United Kingdom-headquartered Provident Financial Plc is engaged in the business of consumer lending. Its areas of operation are divided into segments like Vanquis Bank, CCD and Moneybarn. As on March-16-1962, shares of the Provident Financial Plc got admitted to the London Stock Exchange for trading. Invesco Asset Management Ltd., Woodford Investment Management Ltd., Schroder Investment Management Ltd. and Marathon Asset Management LLP are the major shareholders in the group. The institutional investors hold around 76.13% of the group's total equities (Source: Thomson Reuters).
Trading Update
As on May-03-2019, the group recorded trading statement for the three months ended March-31-2019, during the period under consideration, the group recorded performance in line with the management expectations with Vanquis Bank recorded a new customer growth of 13%, which was higher than the growth recorded in the same period of the previous financial year. Moneybarn has reported record new business volumes and recorded an increase of approximately 40% above Q1 FY18. During the period under review, recovery of home credit continues with new and returning UK home credit customer growth was 27% above the Q1FY18. Satsuma delivered lending volumes, which was 16% higher than the first quarter of FY18 and recorded new business as well.
During the quarter under review, the group completed its Repayment Option Plan refund plan in Vanquis Bank and ongoing investigation by FCA at Moneybarn has come closer to being concluded.
Fundamental Highlights
The group’s performance in terms of Return on Equity, which is an crucial measure of the company’s financial from the shareholders standpoint, was at 9.8% in the FY18, which was below the industry average of 10.86% during the same period and also the five year average ROE of the group was at 18.19% against the industry average ROE of 23.92%.
Stock Performance

Daily Price Chart (as on July 09, 2019), before the market close. (Source: Thomson Reuters)
At the time of writing (before the market close, at 01:54 PM GMT), shares of the PFG were quoting 398.9 and declined by approximately 2.19% against the previous day close. In today's session, its shares have touched a 52w low of GBX 394.6, and in the year-ago period, it has registered a 52w high price of GBX 716 respectively. On a YoY basis, shares of the Provident Financial has plunged by approximately 32%.
Valuation Methodology

Conclusion
The group has recorded decent trading performance in the first quarter of FY19, with strong volume growth in the new business with steady delinquency trends and group’s overall performance was in line with the management expectation for FY19. However, despite decent trading update recorded by the group, its shares were plunging at the LSE and in today’s session, it has registered a new 52w low of GBX 394.6, and also 14-day daily RSI of the stock is strengthening the downside in the stock. Therefore, based on the above discussion and valuation done using the above methodology, we have given a "Watch" recommendation at the current price of GBX 398.9 (as on July-09-2019), before the market close, while we look for any upcoming catalysts in the near term.
*The Speculative Buy recommendation is also valid for the current price as covered in the report (as on July-09-19).
Disclaimer
PLEASE BE ADVISED THAT YOUR CONTINUED USE OF THIS SITE OR THE INFORMATION PROVIDED HEREIN SHALL INDICATE YOUR CONSENT AND AGREEMENT TO THESE TERMS.
References to ‘Kalkine’, ‘we’, ‘our’ and ‘us’ refer to Kalkine Limited.
This website is a service of Kalkine Limited. Kalkine Limited is a private limited company, incorporated in England and Wales with registration number 07903332.
The article has been prepared for informational purposes only and is not intended to be used as a complete source of information on any particular company. Kalkine is not responsible for material posted on this website and does not guarantee the content, accuracy, or use of the content in this site. No advice or information, whether oral or written, obtained by you from Kalkine or through or from the service shall create any warranty not expressly stated.
Kalkine do not offer financial advice based upon your personal financial situation or goals, and we shall NOT be held liable for any investment or trading losses you may incur by using the opinions expressed in our publications, market updates, news alerts and corporate profiles. Kalkine does not in any way endorse or recommend individuals, products or services that may be discussed on this site. You should discuss your portfolios and the risk tolerance level appropriate for your personal financial situation, with a professional licensed financial planner and adviser.

 CA
 NZ
 US
 AU
 IND

 UK
 Please wait processing your request...