Safestore Holdings PLC (SAFE)
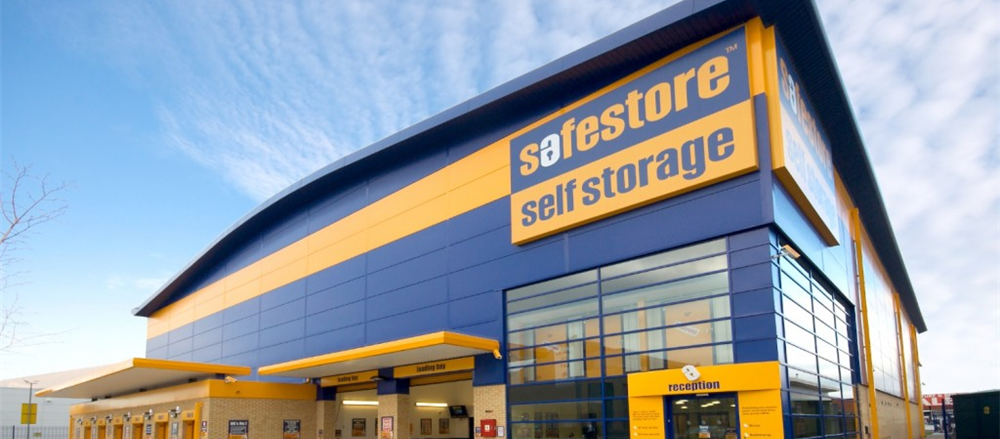
Safestore PLC is the UK’s Largest self-storage group. The group has 146 stores out of which 119 are in the UK and remaining 27 in Paris. The company was incorporated in the year 1998 and is headquartered in Hertfordshire, the United Kingdom. The company's total outstanding market capitalisation stood at £1.24 bn and dividend yield stood at 2.81% (as on March-25-2019).
In the Financial year 2018, Safestore Holding Plc reported revenue of £143.9 million for the period ending October 2018 against £129.9 million for the previous year, same period. There was an increase of 10.8 per cent due to an increase in the revenue from Paris operations and a strong Euro to pound exchange rate. The underlying EBITDA for FY2018 stood at £82.9 million as compared to £74.4 million in FY2017. There was an increase of 11.4 per cent due to strong revenue generated by the company in the current financial year. The underlying profit before tax for FY2018 stood at £62.7 million as compared to £54.2 million in FY2017. EPRA basic earnings stood at £52.7 million in FY2018 against £48.7 million in FY2017.
On 19th March 2019, at the time of writing (before market close, GMT 12:59 PM), Safestore Holdings Plc stock was trading at GBX 593, which was same as its previous day closing price. Stock's 52 weeks High and Low is GBX 620.50/GBX 482.20.
Valuation Methodology

Conclusion
The company had shown good financial growth as compared with the previous year. There had been steady growth in the overseas operations and strong Euro to pound exchange rate. The current trading level indicates the stock movement towards higher levels. The group has strong growth prospects based on the surge in revenue from overseas operations and macro environment favouring towards the company’s growth. Further, valuation based on 20.68x NTM Enterprise Value to EBITDA (approx.) on FY19E EBITDA, which is about £80.56 million, a single-digit upside potential can be seen. In view of the above, we have given a BUY recommendation at the closing price of GBX 593 (as on 18th March 2019).
GVC HOLDINGS PLC (GVC)
GVC Holdings plc works as a public online betting and gaming company in the United Kingdom, Germany, rest of Europe, and internationally. The company currently operates in four divisions: Games labels, sports labels, B2B, and non-core segments. The company's total outstanding market capitalisation stood at £3.02 bn and dividend yield stood at 6.17% (as on March-25-2019).
In FY2018, reported net gaming revenue (NGR) surged by 265% to £2,979.5 million when compared with the last year data mainly due to the FanDuel acquisition in July 2018, although foreign currency translation had a negative impact on the performance. The reported gross profit rose by 248 per cent to £2,004.2 million in FY 2018, from £575.3 million in FY 2017. This reflects policy growth in revenue. Adjusted diluted Earnings Per Share of the group stood at 76.3 pence, up by 75% as compared with the previous year. During FY2018, total dividend per share stood at 32 pence, an increase of 7 per cent from the last year.
Shares of GVC Group PLC were quoting at GBX 544 at the time of writing (as on March 19, 2019, at 1:32 PM GMT), was down by 1.538% against its previous day close price. During the last one-year, shares have registered a 52w high of GBX 1,184.00 and a 52w low of GBX 523.50.
Valuation Methodology

Conclusion
The company has shown an increase in revenue, with the acquisition of Ladbrokes Coral Group PLC, the market leader in online wagering and gaming in the United Kingdom market. Further, valuation based on 8.3x NTM Price to Cash Flow (approx.) on FY19E cash flow per share, which is about 72.37 pence, a single-digit upside potential can be seen. In view of the above, we have given a BUY recommendation at the closing price of GBX 552.50 (as on 18th March 2019).
SEGRO PLC (SGRO)
Segro PLC is a global leader in Real Estate Investment Trust (REITs). The company engages in the UK REIT, warehouses and light industrial property. The company's total outstanding market capitalisation stood at £7.17 bn and dividend yield stood at 2.84% (as on March-25-2019).
On 11th October 2018, Tritax EuroBox PLC of the UK agreed to acquire Segro Plc-Warehouse, a Passo Corese-based lessor of non-residential buildings, from Segro PLC, for a total value of €118 million.
Revenue for the financial year 2018 increased by 10.2 per cent to £ 369.0 million, against £334.7 million in FY 2017. The increase was supported by gross rental income across all the businesses. In FY 2018, operating profit was down by 2.4 per cent to £1,173.4 million as compared to FY 2017 reported data which was £1,201.8 million. Net profit to shareholders surged by 11.5 per cent to £1,062.6 million in FY 2018, against £952.7 million in FY 2017, due to the increase in realised and unrealised gains in both the joint venture and wholly owned portfolios.
Shares of Segro PLC were quoting at GBX 685.60 at the time of writing (as on March 19, 2019, at 1:41 PM GMT), down by 0.175% against its previous day close price. During the last one-year, shares have registered a 52w high of GBX 685.60 and a 52w low of GBX 577.60.
Valuation Methodology

The company growth prospects look favourable with an increase in the operating revenue, acquisitions initiatives in the urban warehouses and recently SGRO stock has breached its 52w high. Further, valuation based on 32x NTM Price to Cash Flow (approx.) on FY19E cash flow per share, which is about 23.91 pence, a single-digit upside potential can be seen. In view of the above, we have given a BUY recommendation at the closing price of GBX 684.40 (as on 18th March 2019).
D4t4 Solutions Plc (D4t4)
D4t4 Solutions Plc is engaged in the distribution, design, installation and support of computer hardware and software systems. The company primarily offers to provide end-to-end management solutions such as customer data platforms, customer analytics, personalisation data, web and mobile design, cloud and managed data services, big data convergence and fraud analytics. The company's total outstanding market capital stood at £94.95 mn and dividend yield stood at 1.06% (as on March-25-2019).
Revenue in the first half of FY19 compared to H1 FY18 rose by 194% to £13.99 million from £4.75 million in H1 FY18. The company reported Operating profit of £3.91milion during H1 FY19 compared to an Operating loss of £0.56 million in H1 FY18. Since the start of FY19, the company has received several new contracts including some big contract from leading US financial services and also several multi-year contracts from a major Scandinavian bank. During the first half of 2018, the company declared an interim dividend of 0.7pence per share, an increase of 12% compared to the corresponding period of the previous year. This was paid on January 10, 2019.
Outstanding market capitalization of £ 94.95 million ranks it among the small-cap category. At the time of writing (as on March 19, 2019) before market close, shares were quoting at GBX 249.0, up by 1.014% against its previous day close. During the last one-year shares have reached a 52w high of GBX 249.80 and a 52w low of GBX 96.0.
Valuation Methodology

Based on decent contracts company has received during first-half of FY19 and reported decent stellar growth in the top-line and earnings in the H1FY19and the valuation done which was based on 22.08x NTM Price to Earnings (approx.) on FY19E earnings per share, which is about 12 pence, a single-digit upside potential can be seen. In view of the above, we have given a Speculative BUY recommendation at the closing price of GBX 246.50 (as on 18th March 2019).
Domino's Pizza Group (DOM)
Domino's Pizza Group PLC is a British pizza delivery company, based in Buckinghamshire, United Kingdom. The group holds the exclusive right to own, operate and franchise branches of Domino's brand in several European countries, including the United Kingdom, and is a major player in the Republic of Ireland and several other markets. The outstanding market capitalisation was around £1.07 billion and a dividend yield of 4.05% per cent.
In FY18, the Group system sales were up 9.0% to £1,259.5 million, driven by system sales growth of 7.1% in the UK & Republic of Ireland and 36.4% growth in the International market. UK like-for-like growth was 4.6%, while like-for-like sales in the Republic of Ireland was up 4.0%. The underlying operating profit for the year stood at £96.9 million, up 1.0% year-on-year; driven by 8.4% rise in underlying operating profits of UK & ROI to £101.0 million, while International operations recorded an operating loss of £4.1 million.
On 19th March 2019, at the time of writing (before market close, GMT 1:15 pm), DOM shares were trading at GBX 235.8, up by 0.46 per cent against its previous day closing price. Stock's 52 weeks High and Low is GBX 390.00/GBX 220.00. The company’s stock beta was 1.11, reflecting more volatility as compared to the benchmark index.
Valuation Methodology

The group faces fierce competition from a range of companies in the market which has the potential to compromise its future performance; competitors include companies exploiting emerging technologies for new food options. Keeping in mind the challenges faced by the company, along with macro headwinds like political uncertainty and risk of inflation,investors should keep a watch on the company at the current levels.
*The Buy or Watch recommendation is also valid for the current price as covered in the report (as on March 19th, 2019).
*All forecasted figures and peers have been taken from Thomson Reuters.
Note- GBp or GBX are interchangeably used for Pence Sterling.
Disclaimer
PLEASE BE ADVISED THAT YOUR CONTINUED USE OF THIS SITE OR THE INFORMATION PROVIDED HEREIN SHALL INDICATE YOUR CONSENT AND AGREEMENT TO THESE TERMS.
References to ‘Kalkine’, ‘we’, ‘our’ and ‘us’ refer to Kalkine Limited.
This website is a service of Kalkine Limited. Kalkine Limited is a private limited company, incorporated in England and Wales with registration number 07903332.
The website has been prepared for informational purposes only and is not intended to be used as a complete source of information on any particular company. Kalkine is not responsible for material posted on this website and does not guarantee the content, accuracy, or use of the content in this site. No advice or information, whether oral or written, obtained by you from Kalkine or through or from the service shall create any warranty not expressly stated.
Kalkine do not offer financial advice based upon your personal financial situation or goals, and we shall NOT be held liable for any investment or trading losses you may incur by using the opinions expressed in our publications, market updates, news alerts and corporate profiles. Kalkine does not in any way endorse or recommend individuals, products or services that may be discussed on this site. You should discuss your portfolios and the risk tolerance level appropriate for your personal financial situation, with a professional licensed financial planner and adviser. Our publications are NOT a solicitation or recommendation to buy, sell or hold.

 CA
 NZ
 US
 AU
 IND

 UK
 Please wait processing your request...