Palo Alto Network Inc
Palo Alto Network Inc (NASDAQ: PANW) is a global AI-driven cybersecurity company offering an integrated portfolio of solutions across network security, cloud security, security operations, AI, and identity. Its platforms include SASE, next-generation firewalls, and cloud-delivered security, along with advanced capabilities through Cortex for threat detection, response, and automation. The company also provides end-to-end cloud security across application lifecycles and leverages its Unit 42 division for threat intelligence, incident response, and cybersecurity consulting to help organizations manage and mitigate cyber risks.

Recent Developments:
- AI Disruption Fears Drive Broad Software Selloff, Weighing on Palo Alto Networks: The software sector is undergoing a challenging phase as initial optimism around artificial intelligence shifts toward concerns over disruption and potential obsolescence, leading to widespread selloffs across Software-as-a-Service companies. Cybersecurity firms, including Palo Alto Networks, have been caught in this broader market reaction, with the company’s stock declining over 35% from its 52-week high despite delivering results that exceeded expectations on key metrics. The decline has been largely driven by fears that AI-driven automation could reduce reliance on third-party security providers. Against this backdrop, the discussion turns toward evaluating Palo Alto Networks’ business fundamentals, recent acquisitions, and financial performance to assess whether the market’s reaction is justified.
Key Growth Aspects
- Strong Revenue Growth Reflecting Sustained Demand: Palo Alto Networks demonstrated solid top-line expansion during Q2 FY26, with total revenue rising to USD 2.6 billion compared with USD 2.3 billion in Q2 FY25, reflecting a 15% year-on-year increase. This growth was supported by broad-based demand across cybersecurity offerings, particularly as enterprises continue to prioritize digital security amid rising cyber threats. The company’s ability to sustain double-digit growth at scale highlights the resilience of its business model and the structural demand tailwinds in cybersecurity.
- Robust Expansion in Next-Generation Security ARR: The company reported strong momentum in its Next-Generation Security Annual Recurring Revenue, which increased by 33% year-on-year to USD 6.3 billion. This reflects accelerating adoption of its platform-based security offerings, particularly in cloud, AI, and security operations. The growth in ARR indicates improving revenue visibility and a shift toward higher-quality, subscription-driven income streams, reinforcing long-term scalability.
- Platformization Strategy Driving Customer Retention and Expansion: Palo Alto Networks continues to benefit from its platformization strategy, which encourages customers to consolidate multiple security solutions within its ecosystem. The company achieved approximately 1,550 total platformizations, reflecting a 35% increase, along with a strong net retention rate of 119%. This indicates that customers not only remain with the platform but also expand their spending over time, enhancing lifetime value and revenue durability.
- Margin Expansion and Operational Efficiency Gains: Profitability improved meaningfully, with non-GAAP operating margins exceeding 30% for the third consecutive quarter and reaching approximately 30.3% in Q2 FY26. This represents an expansion of nearly 190 basis points compared to the prior year. The improvement reflects operating leverage, disciplined cost management, and a higher contribution from software-based revenues, which carry structurally higher margins.
Growth Challenges
- Margin Pressure from SaaS Mix and Scaling Investments: Despite overall margin expansion, services gross margin declined by approximately 100 basis points year-on-year to 75.6%. This was driven by a higher mix of SaaS offerings that are still in the early stages of scaling and therefore carry lower near-term margins. While strategically important, this shift indicates that near-term profitability may remain sensitive to continued investment in high-growth segments.
- Rising Cost Pressures in Supply Chain: The company experienced marginal cost pressures due to higher memory and storage pricing, which impacted product cost of goods sold during the quarter. Although management expects to mitigate this through pricing actions and scale advantages, persistent input cost inflation could weigh on margins if not fully offset.
- Increasing Dependence on Acquisitions for Growth Acceleration: Recent acquisitions such as Chronosphere and CyberArk contributed to growth expectations and future ARR expansion but also introduce integration complexity and financial commitments. The company incurred a significant combined cash outlay of approximately USD 4.9 billion related to these acquisitions, highlighting elevated capital deployment and execution risk associated with integration.
- Hardware Mix Impacting Sequential Margins: While hardware demand improved, the increased mix of hardware revenue led to a sequential decline in product gross margin by approximately 180 basis points compared to the previous quarter. This reflects the relatively lower margin profile of hardware versus software and suggests that fluctuations in product mix can introduce short-term margin volatility.
Key Risks:
- Integration and Execution Risk from Acquisitions: Ongoing integration of CyberArk and Chronosphere may create operational complexity, cost overruns, and delays in realizing expected synergies.
- Margin Sensitivity from Business Mix Shift: Increasing exposure to lower-margin SaaS offerings and hardware mix fluctuations could weigh on overall profitability despite revenue growth.
- Dependence on Sustained Cybersecurity and AI Demand: Any slowdown in enterprise spending on cybersecurity or delays in AI adoption could impact ARR growth and revenue visibility.
- Intensifying Competitive and Technological Landscape: Rapid innovation in cybersecurity and AI-driven solutions increases the risk of product obsolescence and pricing pressure from competitors.
Technical Observation (on the daily chart):
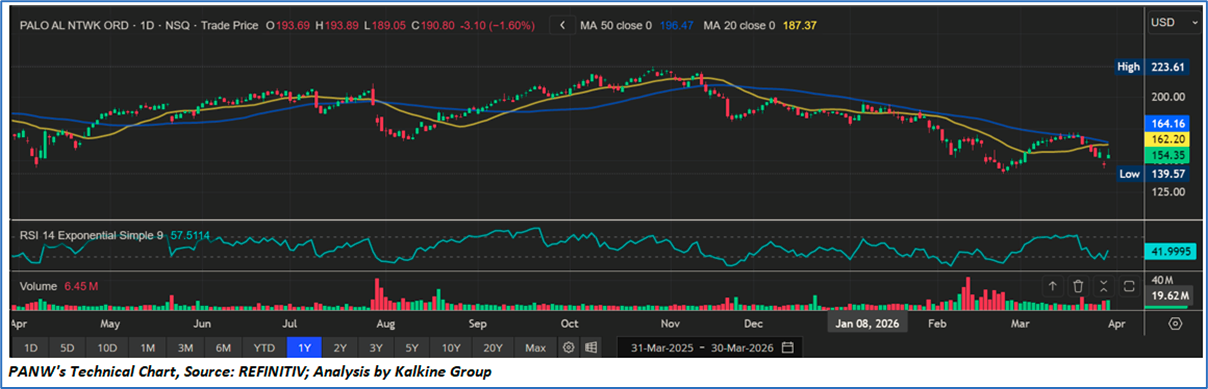
- The stock has transitioned from an uptrend into a sustained corrective phase after peaking near the 223 level, forming a series of lower highs and lower lows, indicating weakening momentum.
- Price is trading below the 50-day moving average and has struggled to reclaim it decisively, while the 20-day moving average remains below the 50-day, reflecting a short-term bearish alignment with intermittent consolidation.
- RSI is hovering around the low-40s, indicating neither oversold nor strong bullish momentum, but still reflecting a weak bias as it remains below the 50 mark.
- Recent rebounds have occurred on relatively muted volume compared to earlier sell-offs, suggesting limited buying conviction and a potential for continued range-bound or downward movement.
Palo Alto Networks delivered a strong Q2 FY26 performance, supported by resilient demand for cybersecurity solutions, with revenue rising to USD 2.6 billion and Next-Generation Security ARR reaching USD 6.3 billion, reflecting continued success of its platformization strategy and growing customer consolidation within its ecosystem. The company also demonstrated improving profitability, with operating margins exceeding 30%, driven by scale benefits and a higher software mix. However, the quarter also highlighted certain pressures, including margin dilution from the expanding SaaS mix, rising input costs within the supply chain, and increased reliance on large-scale acquisitions such as Chronosphere and CyberArk, which introduce integration and capital allocation risks. Additionally, fluctuations in hardware contribution impacted sequential margins, indicating some sensitivity in product mix. Overall, while the company remains well-positioned to capitalize on long-term cybersecurity and AI-driven demand, near-term performance reflects a balance between strong growth momentum and ongoing investment-led pressures.
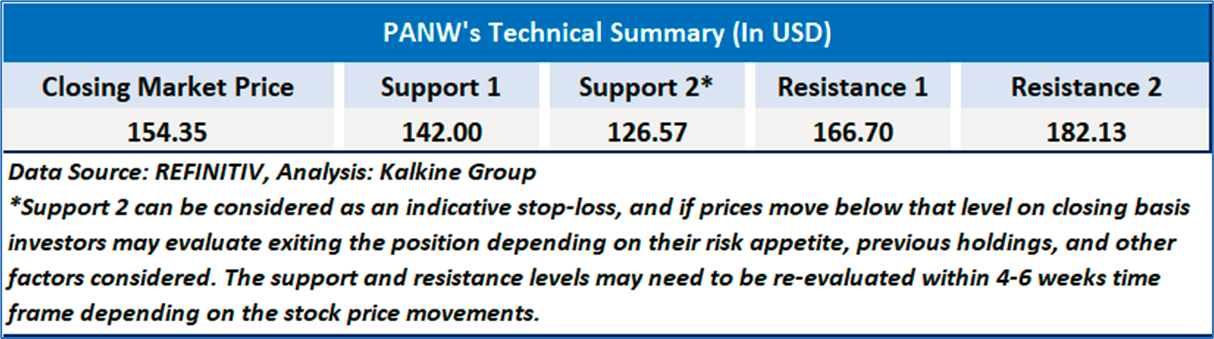
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been Palo Alto Network Inc (NASDAQ: PANW) at the closing market price of USD 154.35 as of March 30,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 30,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 US
 AU
 IND

 UK

 Please wait processing your request...