SolarEdge Technologies, Inc.
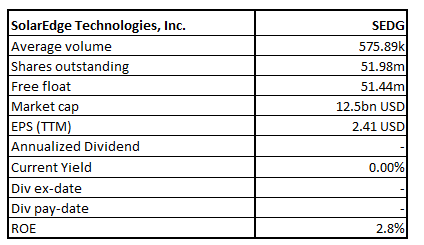
SEDG Details
SolarEdge Technologies, Inc. (NASDAQ: SEDG) is a top player in smart energy technology. It offers energy solutions for residential, commercial and large-scale PV systems. Its product offerings include energy storage systems (ESS), and backup, electric vehicle (EV) components and charging capabilities, home energy management, grid services, power plants, lithium-ion batteries and uninterrupted power supply (UPS).
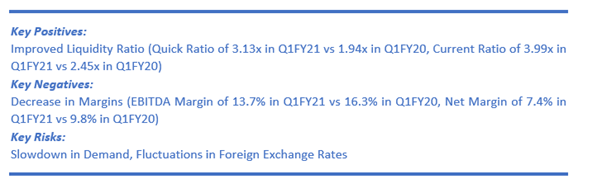
Q1FY21 Results Performance (For the Quarter Ended 31 March 2021)
Rise in Revenue Sequentially: SEDG has recorded a 13% QoQ growth in revenues to $405.5 million as against $358.1 million in the prior quarter. However, the revenues for the quarter declined by 6% YoY.
Net Income Rose 70% QoQ: In GAAP terms, the net income increased by 70% QoQ to $30.1 million, while it was down by 29% YoY. Under non-GAAP, the net income largely remained flat at $55.5 million as compared to $55.7 million in the prior quarter. However, it grew by 10% YoY.
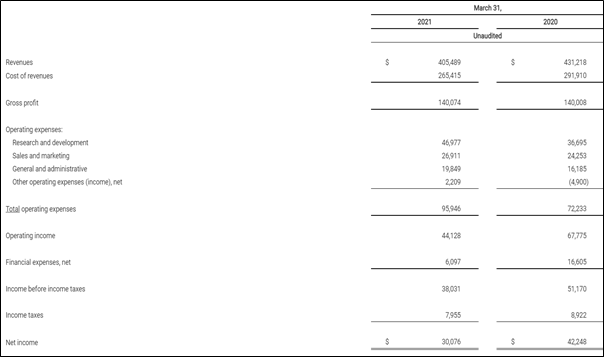
Consolidated Condensed Income Statement (Figures in Thousands) (Source: Company Reports)
Appointment of New Director
The company, on 19 April 2021, declared the induction of Ms. Betsy Atkins to the board of directors effective June 1, 2021. She has a rich experience of leadership and extensive board skill and has an immense global perspective.
Key Risks
Investors should keep an eye on related risks like the rapidly evolving and competitive nature of the solar industry and sustained pressure on gross margin. Further, the company’s performance is susceptible to a reduction in retail prices of electricity from the utility grid, or other renewable energy resources as well as a drop in demand for solar energy solutions, tightening of interest rates, or debt financing, among others.
Outlook
The company continued to witness growth in its solar business across geographies and segments. Driven by its operational performance in Q1FY21, it expects to meet the sustained rise in demand for its residential and commercial products worldwide. Meanwhile, SEDG has guided its revenue in Q2FY21 to stay in between $445 million to $465 million with revenues from solar products to remain in the range of $405 million to $420 million. Further, it has guided its gross margin in Non-GAAP terms to remain between 32% to 34% and Non- GAAP gross margin from the sale of solar products to be in the range of 36% - 38%.
Valuation Methodology: Price/Earnings Per Share Based Relative Valuation (Illustrative)
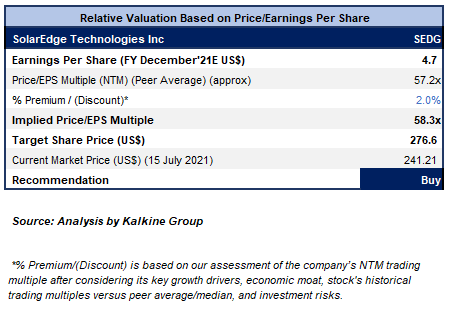
Stock Recommendation
We have valued the stock using Price/Earnings Per Share multiple-based illustrative relative valuation and have arrived at a target price that reflects a rise of low double-digit (in % terms). We have assigned a slight premium to Price/Earnings Per Share Multiple (NTM) (Peer Average) considering its sustained growth in its solar business across geographies and segments, healthy liquidity position and decent outlook. For the purposes of relative valuation, we have taken peers like CEVA Inc (CEVA.OQ), SunPower Corp (SPWR.OQ), Enphase Energy Inc (ENPH.OQ), to name a few. As per NASDAQ, the stock has made a 52-week low and high of $162.60 and $377.00, respectively.
Considering the aforementioned factors, we give a “Buy” recommendation on the stock at the current market price of $241.21 per share, down by 1.73% on 15th July 2021.
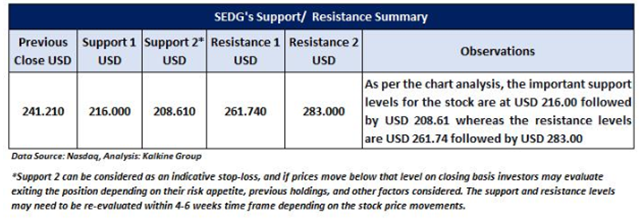
Technical Chart:
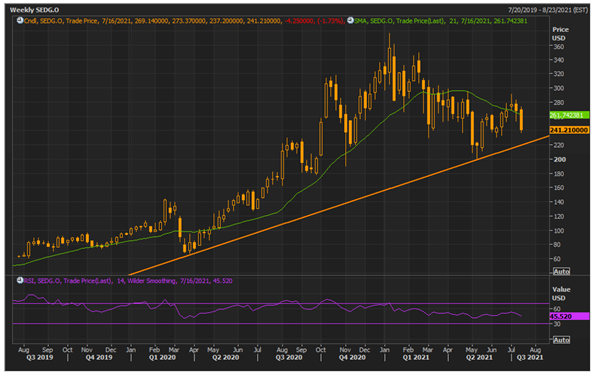
Source: REFINITIV
Sunrun Inc.
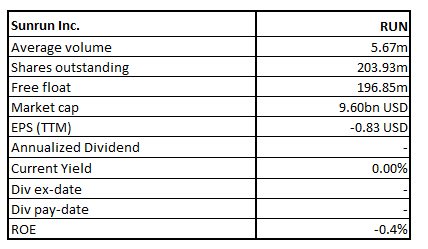
RUN Details
Sunrun Inc. (NASDAQ: RUN) is the top solar company player in the U.S with an entire focus on residential solar systems. It provides home solar, battery storage, and energy services to its customers present across 175 cities in 22 states and Puerto Rico.
Q1FY21 Results Performance (For the Period Ended 31 March 2021)
Solid Revenue growth of 59% YoY: RUN has logged a strong revenue growth of 59% YoY to $334.8 million with revenue from customer agreements and incentives as well as solar energy systems and product sales for the quarter growing by 76% and 44%, respectively. Net subscriber value stood at $8,197 in Q1FY21, ensuing in the generation of a total value of $165 million during Q1FY21.
Customer Additions: Customer additions remained healthy as it added 23,556 customers, including 20,087 subscriber additions that took its customer base to 573,634 as of March 31, 2021.
Increase in Net Loss: Total operating expenses increased significantly by 88% YoY to $513.3 million. Resultantly, net loss attributable to common stockholders increased to $23.8 million.
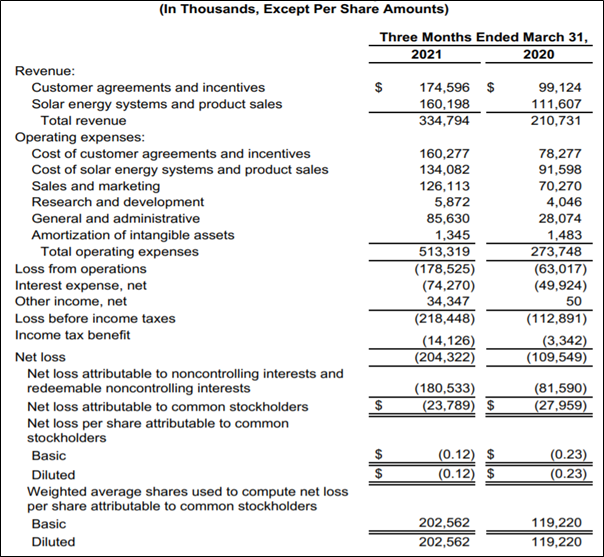
Consolidated Income Statement (Source: Company Reports)
Partnering with Ford
The company, on 19 May 2021, declared that it formed a partnership with Ford Motor Company to assist in the installation of the 80-amp Ford Charge Station Pro and Home integration system for the all-electric F-150 Lightning.
Outlook
The management raised its growth guidance in solar energy capacity installed to 25% to 30% from its earlier prediction of 20-25% growth for 2021 owing to the effect of execution, benefits of scale, differentiated service offering, and competitive position.
Additionally, it now expects to achieve a total value generated of over $750 million in 2021 against its earlier guidance of $700 million. Besides, it reiterated garnering cost synergies of $120 million run-rate by the end of 2021.
Key Risks
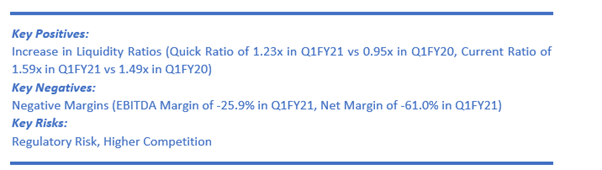
The company’s operations are exposed to risks of supply chain disruptions caused by the outbreak of the pandemic or other natural calamities. Also, the company faces competition from the traditional energy companies as well as solar and other renewable energy companies.
Valuation Methodology: EV/Sales Based Relative Valuation (Illustrative)
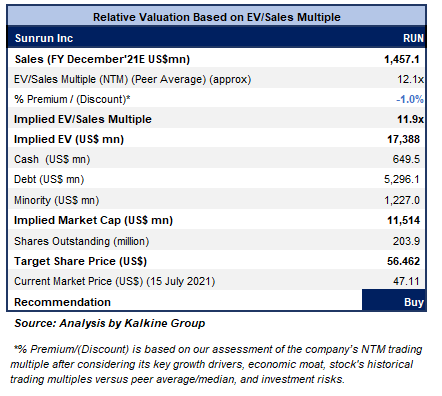
Stock Recommendation
We have valued the stock using an EV/Sales multiple-based illustrative relative valuation and have arrived at a target price that reflects a rise of low double-digit (in % terms). We have applied a slight discount to EV/Sales Multiple (NTM) (Peer Average) considering its higher operating costs, negative earnings in Q1FY21 as well as higher debt levels.
For the purposes of relative valuation, we have taken peers like Vicor Corp (VICR.OQ), Beam Global (BEEM.OQ), among others. As per NASDAQ, the stock has made a 52-week low and high of $34.18 and $100.93, respectively.
Considering its upgrade in guidance along with expanding market reach, healthy liquidity position, and decent growth outlook, we give a “Buy” recommendation on the stock at the current market price of US$47.11 per share, down by 3.26% on 15th July 2021.
Technical Chart:
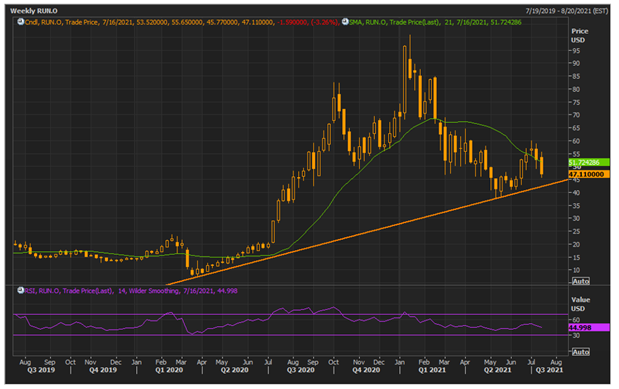
Source: REFINITIV
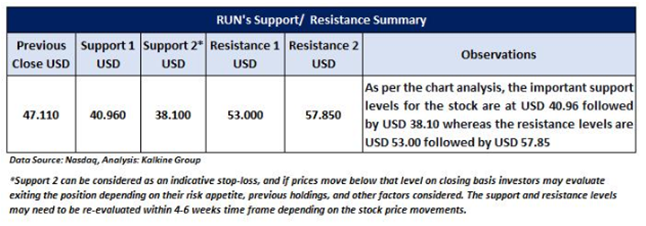
Note 1: The reference data in this report has been partly sourced from REFINITIV.
Note 2: Investment decisions should be made depending on the investors’ appetite on upside potential, risks, holding duration, and any previous holdings. Investors can consider exiting from the stock if the Target Price mentioned as per the analysis has been achieved and subject to the factors discussed above alongside support levels provided.
Technical Indicators Defined:-
Support: A level where-in the stock prices tend to find support if they are falling, and downtrend may take a pause backed by demand or buying interest.
Resistance: A level where-in the stock prices tend to find resistance when they are rising, and uptrend may take a pause due to profit booking or selling interest.
Stop-loss: It is a level to protect further losses in case of unfavourable movement in the stock prices
Disclaimer
References to ‘Kalkine’, ‘we’, ‘our’ and ‘us’ refer to Kalkine Limited.
This website is a service of Kalkine Limited. Kalkine Limited is a private limited company, incorporated in England and Wales with registration number 07903332. Kalkine Limited is authorised and regulated by the Financial Conduct Authority under reference number 579414.
The article has been prepared for informational purposes only and is not intended to be used as a complete source of information on any particular company. No advice or information, whether oral or written, obtained by you from Kalkine or through or from the service shall create any warranty not expressly stated. Kalkine does not intend to exclude any liability which it is not permitted to exclude under applicable law or regulation.
Kalkine does not offer financial advice based upon your personal financial situation or goals, and we shall NOT be held liable for any investment or trading losses you may incur by using the opinions expressed in our publications, market updates, news alerts and corporate profiles. Kalkine does not intend to exclude any liability which it is not permitted to exclude under applicable law or regulation. Kalkine’s non-personalised advice does not in any way endorse or recommend individuals, investment products or services for your personal financial situation. You should discuss your portfolios and the risk tolerance level appropriate for your personal financial situation, with a professional authorised financial planner and adviser. You should be aware that the value of any investment and the income from it can go down as well as up and you may not get back the amount invested.

 CA
 NZ
 US
 AU
 IND

 UK
 Please wait processing your request...