
InterContinental Hotels Group PLC
InterContinental Hotels Group PLC (NYSE: IHG) is a UK-headquartered international hotel group. It operates a broad range of distinct brands across its portfolio. The company manages around 20 hotel brands and the IHG One Rewards loyalty programme, with roughly 6,600 hotels currently open in over 100 countries and a development pipeline exceeding 2,200 additional properties.
As per previous Kalkine’s Global Travel & Leisure Report published on ‘IHG’ on Nov 06, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 125.87 based on fundamental analysis and the stock price has now moved up by ~ 11.50% since then.
Noted below are the details of support and resistance levels provided in our previous report:
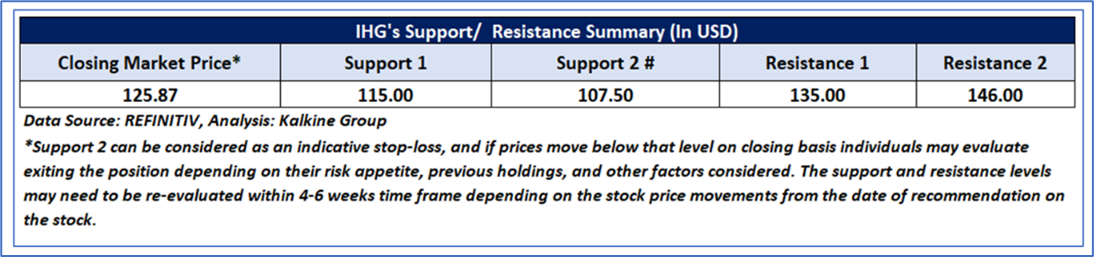
Rationale:
- Softness in U.S. Market Performance: The company continues to experience weaker trading conditions in the U.S., particularly in leisure and group segments. In Q3 2025, U.S. RevPAR declined by 1.6% year-on-year, driven by lower government travel volumes, reduced international inbound demand and event-related timing effects. This softness has weighed on overall Americas performance, where regional RevPAR declined 0.9% during the quarter.
- Pressure on Leisure and Group Demand: Demand from leisure and group travellers in key markets has softened compared with prior-year peaks. Globally in the first half of 2025, group room revenue declined by 1% and leisure by 1%, reflecting both tougher prior-year comparatives and macroeconomic caution among consumers. This shift places greater reliance on business travel growth to sustain RevPAR momentum.
- Currency and Financing Cost Headwinds: Higher borrowing levels and funding costs have contributed to increased finance expense. Adjusted interest expense rose 15% year-on-year to $91 million in H1 2025, reflecting higher debt balances and rates. This creates incremental pressure on earnings and cash generation despite strong operational delivery.
- Ongoing Weakness in Mainland China Rate Growth: While the Chinese market is recovering gradually, rate performance remains subdued in parts of the mainland. In Q3 2025, Greater China RevPAR declined 1.8% year-on-year, with ADR falling 2.7%, particularly across Tier 2–4 cities where increased outbound leisure travel reduced local demand. This highlights an uneven recovery profile across the region.
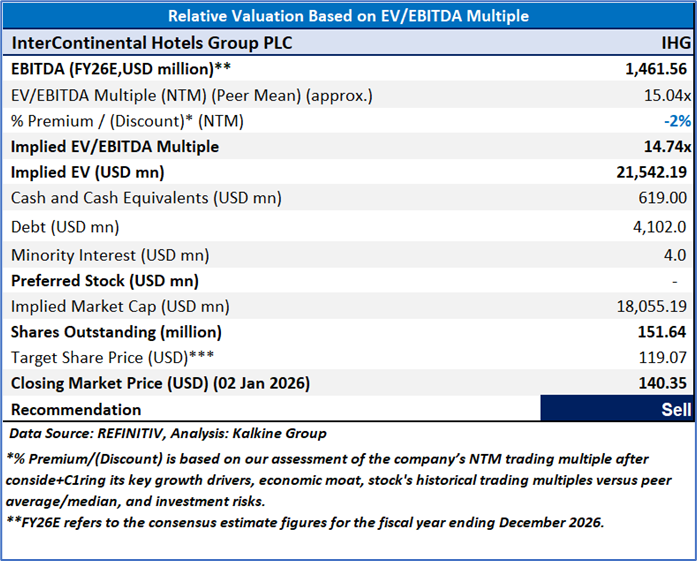
Valuation (Using EV/EBITDA Multiple)
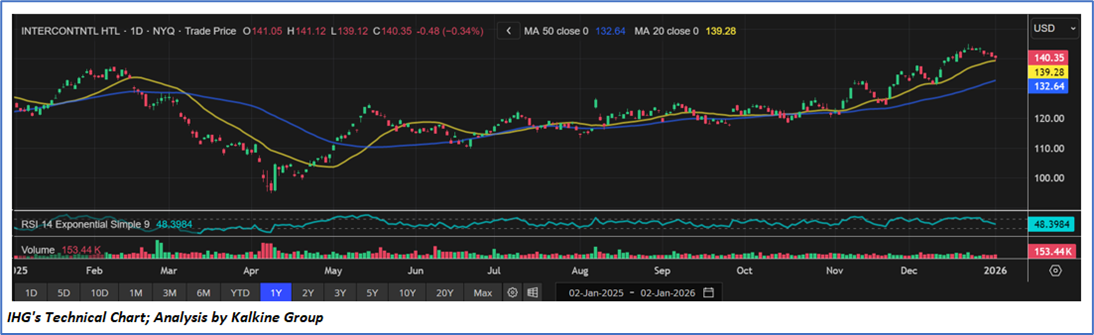
Share Price Chart
Conclusion
IHG’s recent performance highlights several emerging pressures that weaken the near-term outlook. Trading softness in the U.S. market remains evident, with regional RevPAR declining 0.9% in Q3 2025, including a 1.6% drop in the U.S., driven by weaker leisure and group demand, reduced government travel and softer inbound tourism. Meanwhile, Greater China continues to show uneven recovery, with RevPAR down 1.8% and rates declining 2.7% in the quarter, particularly across lower-tier cities. At the same time, higher leverage and rising borrowing costs pushed adjusted interest expense up 15% year-on-year in H1 2025 to $91 million, creating incremental earnings pressure despite system growth. Together, these trends signal a more challenging near-term trading environment, with geographic recovery still inconsistent and macro-sensitive segments showing demand fragility.
Based on the notional gains, valuation downside and price action stance, a "Sell" recommendation on InterContinental Hotels Group PLC (NYSE: IHG) has been given at the closing market price of USD 140.35 as on 02 January 2026.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 02 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 CA
 NZ
 US
 AU
 IND

 UK

 Please wait processing your request...