.png)
Antofagasta PLC
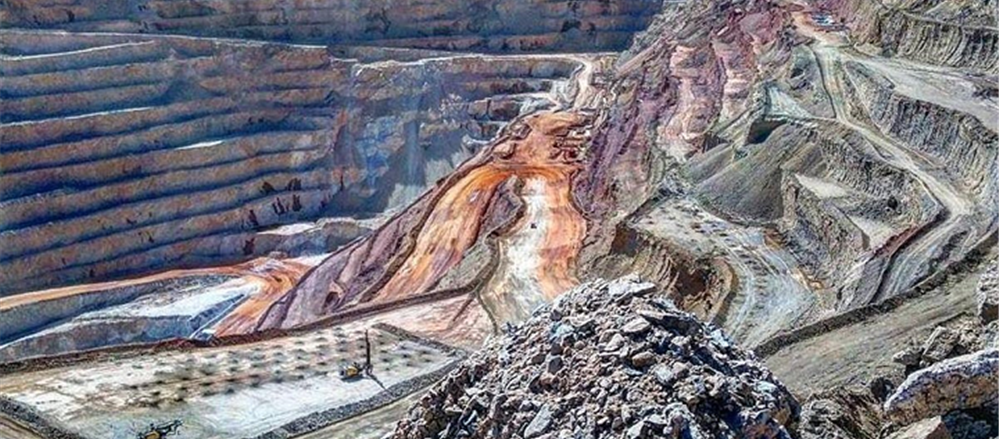
Antofagasta PLC (ANTO) is a Chile-based copper mining group with four copper mines in Chile and interests in transport business providing rail and road cargo services in northern Chile mainly to mining customers. The group also has a portfolio of growth opportunities located mainly in Chile and focuses on exploration activity to expand its mineral resource base in Chile and abroad, particularly in the Americas. The operations of the group are differentiated in seven operating segments, namely Los Pelambres, Centinela, Antucoya, Zaldívar, Exploration and evaluation, Corporate and other items, and Transport division.
Recent Development
The company on 15 July 2019 announced that Pakistan had been ordered to pay $5.84 billion in damages to Tethyan Copper Company by International Centre for Settlement of Investment Disputes, a part of World Bank. The case was in relation to the unlawful denial of a mining lease in 2011 for the Reko Diq project in Pakistan, and the Tethyan Copper Company is a joint venture held equally by Antofagasta and Barrick Gold Corporation. There are limited grounds for challenging the award, which is binding on the parties.
Financial Highlights (1H FY 2019, in $m)
.png)
(Source: Company Filings)
Due to an increase in gold revenues and a 25.1% increase in copper sales volumes, revenue was 19.1% higher than in the same period of last year to $2,525.6 million. The rise in revenue was despite lower realised molybdenum prices and 6.3% fall in realised copper prices. Despite an increase of $133.6 million in total operating costs from $1,600.3 million in H1 2018 to $1,733.9 million in H1 2019, operating profit from subsidiaries rose in HY 2019 by 52.1% to $791.7 million (H1 2018 - $520.4 million). As revenue rose due to higher production of cooper, EBITDA from the mining division increased by $402.3 million or 46.9% to $1,260.8 million, leading to 44.4% increase in group EBITDA to 1,305.9 million, which corresponded to an EBITDA margin of 51.7%.
Profit before tax increased by 63.9% to $763.0 millionin the first half of 2019 (H1 2018 $465.6 million), while profit for the period amounted to $490.4 million, which was up from $315.7 million reported in the corresponding period of last year. Profit attributable to the owners of the parent group rose by $108.1 million to $302.4 million from $194.3 million in the first six months of 2018, while earnings per share from continuing and discontinued operations were 30.7 cents per share (H1 2018 – 19.8 cents per share). Representing a net debt/EBITDA ratio of 0.20X on higher cash flow from operations, net debt stood at $517.4 million during the current period.
Valuation Methodology
Method: EV/EBITDA Approach (NTM)
.png)
Share Price Commentary
.png)
Daily Chart as at 22-August-19, before the market closed (Source: Thomson Reuters)
On 22 August 2019, at the time of writing (before the market closed, GMT 9:15 am), ANTO shares were trading at GBX 808.00, down by 1.22 per cent against the previous day closing price. Stock's 52 weeks High and Low are GBX 1,026.00/GBX 713.20. The company's stock beta was 1.37, reflecting more volatility as compared to the benchmark index. Total outstanding market capitalisation was around £8.10 billion, with a dividend yield of 4.10%.
Conclusion
Boosted by lower cost of production and higher copper sales, the company reported a better-than-expected first-half results, despite an unfavourable macro environment which has seen copper prices hit their lowest level in two years this month and decline by 4% this year. The company noted the uncertainty caused by the continuing trade dispute between the USA and China, which has affected copper prices as it is widely used in electrical components and renewable energy. The company expect to end the year with record copper production, as it expects the rate of copper production to continue into the second half of 2019, with copper production guidance for the full year remaining unchanged at 750-790,000 tonnes. The company was successful in improving the EBITDA margin, reflecting stronger copper production and lower unit costs. It also reduced its net cash costs by 33c/lb to $1.19/lb, driven by successful Cost and Competitiveness Programme, and the net cash cost guidance for the year has been reduced by 5c/lb to $1.25/lb.
Based on the decent prospects, and supported by valuation undertaken using the above method, we have given a “BUY” recommendation at the current price of GBX 808 (as on 22 August 2019) with single digit upside potential based on 4.49x NTM EV/EBITDA (approx.) on FY19E EBITDA (approx.).
Premier Oil PLC
Premier Oil Plc (PMO) is a London, United Kingdom-headquartered multinational oil and gas exploration and production company, with reserves and resources of around 867 million barrels of oil equivalent as at 31 December 2018. The company has oil and gas interests in Latin America, the Falkland Islands, South East Asia and the North Sea, where the group seeks to invest in high-quality opportunities.
On 14th November 2019, the company will announce Trading & Operation Update.
Financial Highlights (H1 FY2019, US$ million)
.png)
(Source: Interim Report, Company Website)
In H1 FY19, the company’s sales revenue increased to $871.30 million as compared with the corresponding period of the last year. Profit after tax for the current period stood at $120.6 million, an increase from $98.4 million in H1 FY18. Basic earnings per share surged by 1.5 cents to 14.7 cents against the 13.2 cents in H1 FY18. EBITDAX rose by $192.4 million to $680.2 million as compared to $487.8 million in H1 FY18, driven by the improved production and realised oil prices post hedging with costs remaining approximately flat due to tight cost control.
Opex was $10 per boe plus lease costs of $6 per boe. The company’s cash margin increased by 35 per centagainst the previous year same period data. Free cash flow increased to $182 million as compared to a cash outflow of $90 million in H1 FY18. On 30th June 2019, net debt declined to $2.15 billion (31 December 2018: $2.33 billion). For the first half of 2019, the company production averaged 84.1 kboepd, an increase of 10 per cent as compared with the corresponding period of the last year.
Share Price Performance
.png)
Daily Chart as at August-22-19, before the market closed (Source: Thomson Reuters)
On 22nd August 2019, at the time of writing (before the market close, GMT 11:45 AM), Premier Oil Plc shares were trading at GBX 75.322 and increased by 4.23% against the previous day closing price. Stock's 52 weeks High and Low are GBX 146.90/GBX 54.70.
Valuation Methodology
.png)
*Currency exchange rate taken for 1 USD = 0.823834 GBP.
*Peers: Genel Energy PLC, EnQuest PLC, Tullow Oil PLC, and Caim Energy PLC.
Conclusion
Oil and gas prices can be subject to significant fluctuations, and as the prices are affected by global supply and demand, the company does not have any influence on the market prices, which can lead to a significant impact on the financials and affect business assumptions.
The company had started a process to sell its holdings in the coast of Mexico, which is an undeveloped project, and also decrease its holding in a long-awaited scheme in waters north of the Falkland Islands. The company also decided to sell roughly 15% holdings in the Zama field. The Zama sales process would lead to a material decrease in debt levels.
The company reduced net debt to $2.15 billion, helped by high operating efficiencies and strong free cash flow. The group reported that it was on track to meet its previously upgraded full-year production guidance of 75-80 kboepd and it expects first gas from the Gajah Puteri, Iguana and Bison fields in Indonesia by the end of the year. The company operated the Tolmount development project and remained on schedule and within the budget, and the project is set for the first gas production by the end of 2020.
The company had reported another robust performancewhere they had exceeded the operational and financial targets for the current period. The company has reduced its debt considerably and seeks to improve its leverage position further, and the Sea Lion farm-down and the Zama divestment processes are expecting an additional strengthening of the balance sheet, which ruins the company’s uppermost priority.
Based on the above factors and supported by valuation done using the above method, we have given a “Speculative Buy” recommendation at the closing price of GBX 72.26 (as on 21st August 2019) with lower double-digit upside potential, based on 8.11x NTM Price/Earnings multiple (approx.) on FY19E earnings per share (approx.).
*All forecasted figures and peers have been taken from Thomson Reuters.
*Speculative Buy recommendation is also valid at the current price as on August-22-2019.
Disclaimer
PLEASE BE ADVISED THAT YOUR CONTINUED USE OF THIS SITE OR THE INFORMATION PROVIDED HEREIN SHALL INDICATE YOUR CONSENT AND AGREEMENT TO THESE TERMS.
References to ‘Kalkine’, ‘we’, ‘our’ and ‘us’ refer to Kalkine Limited.
This website is a service of Kalkine Limited. Kalkine Limited is a private limited company, incorporated in England and Wales with registration number 07903332.
The article has been prepared for informational purposes only and is not intended to be used as a complete source of information on any particular company. Kalkine is not responsible for material posted on this website and does not guarantee the content, accuracy, or use of the content in this site. No advice or information, whether oral or written, obtained by you from Kalkine or through or from the service shall create any warranty not expressly stated.
Kalkine do not offer financial advice based upon your personal financial situation or goals, and we shall NOT be held liable for any investment or trading losses you may incur by using the opinions expressed in our publications, market updates, news alerts and corporate profiles. Kalkine does not in any way endorse or recommend individuals, products or services that may be discussed on this site. You should discuss your portfolios and the risk tolerance level appropriate for your personal financial situation, with a professional licensed financial planner and adviser.

 CA
 NZ
 US
 AU
 IND

 UK
 Please wait processing your request...